Eric Kachman is volunteer on Wolf-PAC ’s communications team.
The crashes of 1929 and 2008 share similar origins: a lack of appropriate oversight and regulation. Irresponsible banking practices, bad investments and rampant stock market speculation preceded the 1929 crash. The resulting panic collapsed the economy, with unemployment peaking at more than a quarter of the population. Similarly, the crash of 2008 came about due to real estate speculation, and apparently foolish lending and borrowing, spiking foreclosures between 2008 and 2010.
Banks forced millions from their homes, and jobs became scarce in the resulting downturn. With Covid-19, a similar economic situation holds today, especially for those just entering the job market.
Such economic crises have been devastating. In their wake, we have tried drafting legislation to prevent recurrence. However, even after 2008, proposed protections have been blocked or rendered ineffective by the banking industry’s immense influence in Washington, D.C. To ensure a stable and healthy economy, we must enact campaign finance reforms to reduce the power of the banking lobby.
Separating investment banks from commercial banks
Common sense laws and institutions created during the Depression prevented a recurrence for generations. Those achievements included passage of the Glass-Steagall Act and creation of the Federal Deposit Insurance Corporation. Glass-Steagall separated commercial from investment banks, recognizing that commercial retail banks function very differently from investment banks. They’re both essential, but cannot safely exist as a single entity.
Commercial banking is the workhorse of our economy, providing essential everyday services: storing, lending, managing and transferring money. By contrast, investment banks are the racehorses of the financial world. They seek out innovation, and take risks — they play the stock market. They can be engines of economic growth. When the economy is poor, or when they make bad decisions, they risk going under. This is fair: high risk, high reward.
However, investment banks should not subject us all to that risk. Glass-Steagall created a barrier between these two equally important banking functions. Without this firewall, the money we entrust to a bank can be used to gamble on the stock market. If the economy and stock market tank, people can’t withdraw their money — it no longer exists.
Unlearning lessons
So what happened? How did we unlearn the lessons of the Depression? The answer is the Gramm-Leach-Bliley Act, created by and for the banking industry in 1999. Though styled as a banking “modernization” act, GLBA only reflected the increasing influence of massive campaign donations.
President Bill Clinton publicly vowed to spend no more than the legal limit on campaigning in 1996, but he subverted the law in part by raising money for the Democratic National Committee, making that organization part of his campaign. Breaking promises was nothing new, and still seems the rule. Campaign contributors buy access and influence decision making. Clinton received huge donations from the banking industry, particularly from Goldman Sachs. As a reward, Clinton made Robert Rubin — a major proponent of GLBA who had worked 26 years at Goldman Sachs — Treasury secretary.
GLBA meant deregulation. Resulting mergers and acquisitions again melded commercial and investment banking. They created “too big to fail,” in a sense rendering FDIC protections moot. After all, the FDIC insures depositors against bank failure. The FDIC protects you and me; GLBA protects gluttonous bankers.
The bailout
The bank bailout of 2008 was sold as a cure for the Great Recession, reviving the economy by freeing up credit. In reality, few banks eased credit. As noted by Mike McIntire in The New York Times, the bailout program was “ a no-strings-attached windfall that could be used to pay down debt, acquire other businesses, or invest for the future.”
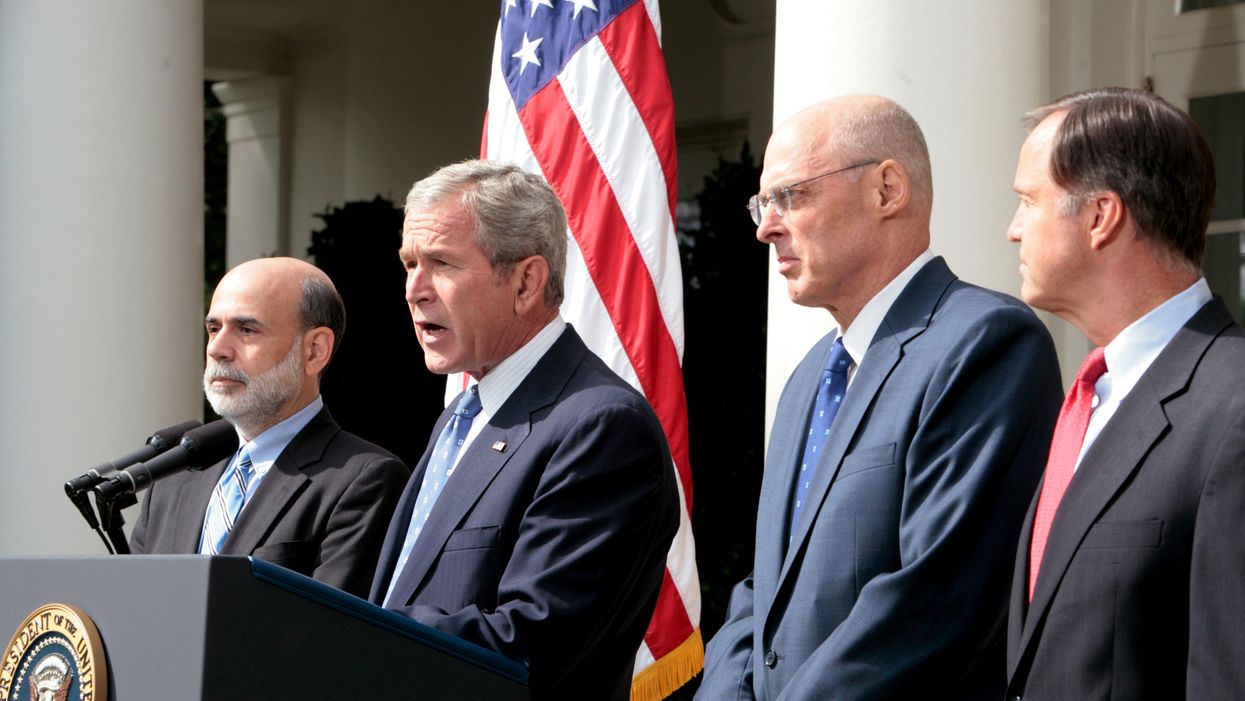
Banks should serve society but, regardless of what politicians might say, they make us serve the banks. Both parties are complicit. Clinton gave us GLBA; George W. Bush gave us the bank bailout of 2008; Barack Obama’s attempts at reform largely fell flat. For example, to assist financially stressed homeowners, the Obama administration started programs such as the Home Affordable Modification Program. However, banks participating in HAMP rejected 72 percent of the applications, denying help to 4 million citizens.
The root of the problem
Just bringing back Glass-Steagall isn’t the solution. Of course we must separate commercial and investment banks, but that’s not enough. When a mixed commercial/investment bank fails, it wipes out depositors’ savings; when such a bank is too big to fail, that means it impacts a huge portion of the population. When Congress bails out such a failed bank, we pay for it through our taxes. The moral hazard provided by the FDIC or, worse, assurance of a massive bailout, means that the reckless behavior of banks is no longer the bank’s issue, but ours. They privatize the profits and socialize the risk, and we foot the bill. So besides bringing back banking regulation, we must also attack the root of the problem. Only common sense controls on campaign financing can curb the undue influence of the banking industry in Congress.
Are you a customer of JP Morgan Chase? They gave $5,800,208 during the 2020 election cycle. Are you a customer of Capital One? Their financial PAC gave $623,000. Citadel Asset Management donated 13 million dollars. These are not charitable donations. These millions buy political favor, of both Republican and Democratic candidates. Such big money largely controls electoral races at every level — local, state, and federal — protecting their interests at the expense of the public.
A real solution
Neither the Great Depression nor the Great Recession were at all unique. Such crises will happen again as corrupt politicians attack regulations and protect bankers. However, we can address the issue by amending the U.S. Constitution to control campaign financing, removing the corrupting influence of money from our elections. We could thus elect representatives who truly represent us, protecting citizens from rapacious banking. You can help make this change by joining Wolf-PAC, a volunteer organization dedicated to bringing about such an amendment.