
Goldstone’s latest book is “Not White Enough: The Long, Shameful Road to Japanese American Internment.” Learn more at www.lawrencegoldstone.com.
In a key scene in the classic Frank Capra film, “It’s a Wonderful Life,” George Bailey (played by a noble, sincere James Stewart), faced with a run on his family-owned bank instigated by the evil, grasping Old Man Potter (played by a sneering Lionel Barrymore), tries to convince his friends and neighbors that their money is safe, even though he cannot meet their demands of mass withdrawals. He tries to explain that “the money isn’t here in the safe,” but has allowed the citizens of Bedford Falls to build homes and finance their needs at a reasonable price. If Potter is allowed to take over the bank, he warns, “There will never be another decent home built in this town.”
At first, he gets nowhere. The deposits are not insured and those who have mobbed the bank, although they like George personally, are terrified the bank will run out of money and they will be left with nothing. George, pleading with them to listen, is forced to pay out cash to a couple of the depositors who remain unmoved. But soon his pleas begin to sway the men and women he has known all his life and who have been doing business with the bank since his father began it. The demand for withdrawals ceases, the bank is saved, and Potter is foiled.
In the end, there was only one thing that could have convinced the frightened, skeptical townsfolk to change their minds.
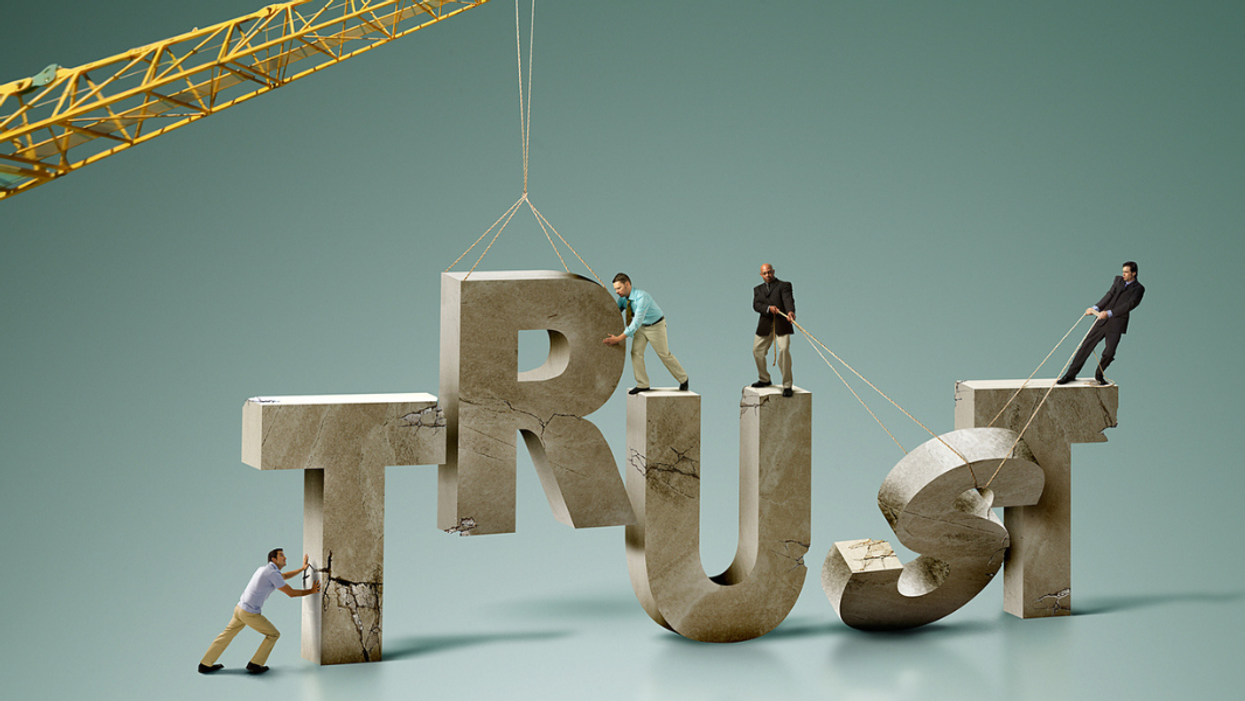
Trust.
That is the way banking works. It is, at its core, a fragile system. No bank could ever meet a demand for total withdrawals by even a fraction of its customers because the money has either been loaned out or invested. Insured deposits have changed the equation somewhat, as has federal oversight, but, as Silicon Valley Bank found out, the principle remains sound. Bedford Falls Savings and Loan survived and Silicon Valley Bank failed because although SVB’s balance sheet was technically sound, it had lost the trust of many of its largest depositors.
Banking is not the only institution whose assets are ephemeral and that cannot function without trust.
Democracy is another.
Unlike in autocratic systems of government, be they monarchies, oligarchies, or dictatorships, democracy is unique in that it requires “consent of the governed.” Such consent may be grudging, but without it, the system will collapse. And that consent will not be granted unless the participants trust that the system is not so dishonest or so unfair that working within it is fruitless. If that occurs, conflict resolution, the key to success for any democracy, will move from the institutions of government to the streets or the battlefields.
There is little question that conflict resolution and the trust required to keep it within peaceful bounds is under great strain in the United States. In effect, what America is faced with is nothing less than a potential run on democracy.
The current loss of trust in government is, alas, not unique in United States history and the precedent is frightening. When Abraham Lincoln was elected president, slave states lost total trust in the federal government’s willingness to allow the perpetuation of slavery. Without even waiting to see how Lincoln would deal with the problem, they abandoned the Union and perpetrated a Civil War in which hundreds of thousands of Americans died, even more were maimed, and the loss of property was immense. Less than two decades later, only a last-minute compromise over the disputed presidential election of 1876 saved a second civil war, with thousands who thought Samuel Tilden should have been declared the winner rather than Rutherford B. Hayes—they were probably correct—massed outside Washington, prepared to march on the capital and install Tilden by force.
On January 6, 2021, of course, thousands loyal to defeated President Donald Trump did march on Washington, storming the capitol with the stated intent of installing Trump by force. Those who participated in the January 6 insurrection had lost trust in the integrity of the electoral process and many of them for American democracy in general.
Whether they were hoodwinked by Trump, acting in convenient political self-interest, or frustrated by a government that seemed no longer to care about them is unimportant. Their loss of faith was real and so was the violence to which they resorted and hoped would spread across the nation. Trump, who cares nothing for either democracy or those who revere him, gives every indication of attempting to incite the same sort of uprising again.
Where the electoral system has lost the trust of the right, the judiciary, especially the Supreme Court, has lost the trust of the left. Decisions such as Citizens United, Shelby County v. Holder, and especially Dobbs v. Jackson Women’s Health Organization, have been condemned by both the far and moderate left as purely political, leading to widespread accusations that the six conservative justices are merely “politicians in robes.” Calls for reform, including the extreme measure of adding four new justices, became so widespread that President Biden appointed a commission to study possible changes. So far, the commission’s recommendations, which were not at all definitive, have come to nothing, a situation unlikely to change.
How most on the left will react to the loss of trust in the courts is not clear. At the very least, there may be segments, perhaps in state and local governments, that simply choose to ignore the law and behave as they please, hardly a prescription for healthy governance. Others, like those on the extreme right, may choose violence.
Because it requires the trust of the citizenry to survive, democracy, like banking, is a fragile system. In the United States, both the electoral process and the rule of law are fundamental precepts and if either cannot keep the trust of the people, the nation may lose its democratic identity more quickly than many may think. To complicate the problem, once lost, trust is not easily regained.
That civil discourse and constructive problem solving in American politics are in crisis is all too apparent. But the crisis of trust is the nation’s biggest threat. In film, a Frank Capra can fashion a George Bailey to come to the rescue. In real life, it is a good deal more difficult.




 Scenes from Favela Rocinha, Brazil - (R-L) Rows of brick homes, Hugo Balta on a motorcycle taxi, and steep, winding roadsHugo Balta