Vidhura S. Tennekoon is an Assistant Professor of Economics at Indiana University.
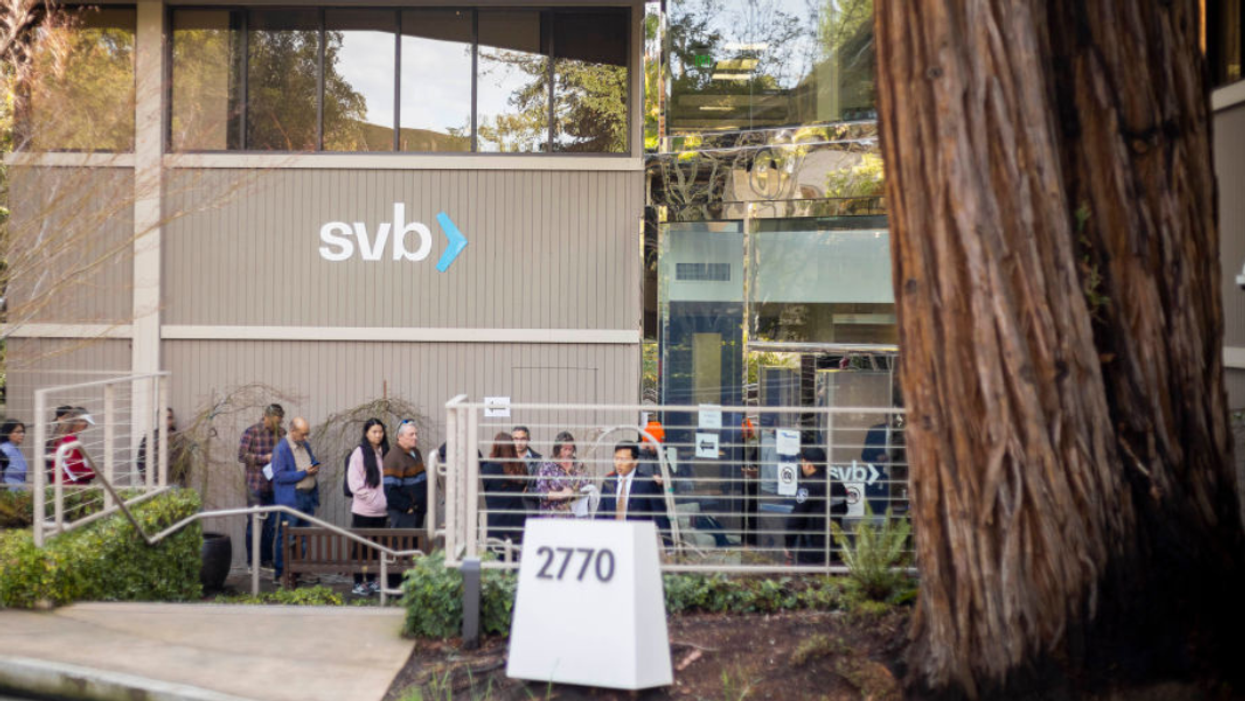
Silicon Valley Bank and Signature Bank failed with enormous speed – so quickly that they could be textbook cases of classic bank runs, in which too many depositors withdraw their funds from a bank at the same time. The failures at SVB and Signature were two of the three biggest in U.S. banking history, following the collapse of Washington Mutual in 2008.
How could this happen when the banking industry has been sitting on record levels of excess reserves – or the amount of cash held beyond what regulators require?
While the most common type of risk faced by a commercial bank is a jump in loan defaults – known as credit risk – that’s not what is happening here. As an economist who has expertise in banking, I believe it boils down to two other big risks every lender faces: interest rate risk and liquidity risk.
Interest rate risk
A bank faces interest rate risk when the rates increase rapidly within a shorter period.
That’s exactly what has happened in the U.S. since March 2022. The Federal Reserve has been aggressively raising rates – 4.5 percentage points so far – in a bid to tame soaring inflation. As a result, the yield on debt has jumped at a commensurate rate.
The yield on one-year U.S. government Treasury notes hit a 17-year high of 5.25% in March 2023, up from less than 0.5% at the beginning of 2022. Yields on 30-year Treasurys have climbed almost 2 percentage points.
As yields on a security go up, its price goes down. And so such a rapid rise in rates in so short a time caused the market value of previously issued debt – whether corporate bonds or government Treasury bills – to plunge, especially for longer-dated debt.
For example, a 2 percentage point gain in a 30-year bond’s yield can cause its market value to plunge by around 32%.
SVB, as Silicon Valley Bank is known, had a massive share of its assets – 55% – invested in fixed-income securities, such as U.S. government bonds.
Of course, interest rate risk leading to a drop in market value of a security is not a huge problem as long as the owner can hold onto it until maturity, at which point it can collect its original face value without realizing any loss. The unrealized loss stays hidden on the bank’s balance sheet and disappears over time.
But if the owner has to sell the security before its maturity at a time when the market value is lower than face value, the unrealized loss becomes an actual loss.
That’s exactly what SVB had to do earlier this year as its customers, dealing with their own cash shortfalls, began withdrawing their deposits – while even higher interest rates were expected.
This bring us to liquidity risk.
Liquidity risk
Liquidity risk is the risk that a bank won’t be able to meet its obligations when they come due without incurring losses.
For example, if you spend US$150,000 of your savings to buy a house and down the road you need some or all of that money to deal with another emergency, you’re experiencing a consequence of liquidity risk. A large chunk of your money is now tied up in the house, which is not easily exchangeable for cash.
Customers of SVB were withdrawing their deposits beyond what it could pay using its cash reserves, and so to help meet its obligations the bank decided to sell $21 billion of its securities portfolio at a loss of $1.8 billion. The drain on equity capital led the lender to try to raise over $2 billion in new capital.
The call to raise equity sent shockwaves to SVB’s customers, who were losing confidence in the bank and rushed to withdraw cash. A bank run like this can cause even a healthy bank to go bankrupt in a matter days, especially now in the digital age.
In part this is because many of SVB’s customers had deposits well above the $250,000 insured by the Federal Deposit Insurance Corp. – and so they knew their money might not be safe if the bank were to fail. Roughly 88% of deposits at SVB were uninsured.
Signature faced a similar problem, as SVB’s collapse prompted many of its customers to withdraw their deposits out of a similar concern over liquidity risk. About 90% of its deposits were uninsured.
Systemic risk?
All banks face interest rate risk today on some of their holdings because of the Fed’s rate-hiking campaign.
This has resulted in $620 billion in unrealized losses on bank balance sheets as of December 2022.
But most banks are unlikely to have significant liquidity risk.
While SVB and Signature were complying with regulatory requirements, the composition of their assets was not in line with industry averages.
Signature had just over 5% of its assets in cash and SVB had 7%, compared with the industry average of 13%. In addition, SVB’s 55% of assets in fixed-income securities compares with the industry average of 24%.
The U.S. government’s decision to backstop all deposits of SVB and Signature regardless of their size should make it less likely that banks with less cash and more securities on their books will face a liquidity shortfall because of massive withdrawals driven by sudden panic.
However, with over $1 trillion of bank deposits currently uninsured, I believe that the banking crisis is far from over.
This article originally appeared in The Conversation.




 Scenes from Favela Rocinha, Brazil - (R-L) Rows of brick homes, Hugo Balta on a motorcycle taxi, and steep, winding roadsHugo Balta