Skip to content
Search

Latest Stories

Follow Us:
Top Stories

Congress shows signs of bipartisanship with retirement benefits bill

Opinion

401k statement
DNY59/Getty Images

Lopez is president of the Hispanic Leadership Fund, a nonpartisan public policy advocacy organization that advances liberty, opportunity and prosperity for all.

With financial insecurity looming in the consciousness of millions of Americans, it was encouraging to see the U.S. House of Representatives recently passed legislation that strengthens and expands opportunities for those who participate in private retirement plans through their employer. Tens of millions of Americans stand to benefit from potential changes in the law.

The Securing a Strong Retirement Act, often referred to as SECURE 2.0, passed the chamber with overwhelming bipartisan support (by a vote of 414-5) — which is in and of itself eyebrow-raising these days.


The bill includes a series of critical changes that will help small businesses and their employees, lower- and middle-income families, and anyone attempting to save and improve their economic outlook.

One of the most important provisions of SECURE 2.0 is enhancement of the Saver’s Credit, a tax credit available to low- and moderate-income workers who make contributions out of their salary to their employer-sponsored 401(k), 403(b), SIMPLE, SEP or governmental 457 plan, or who contribute to traditional or Roth IRAs.

Under current law, the credit percentage — which is multiplied by the contribution (up to the maximum contribution of $2,000) — is 50 percent, 20 percent, 10 percent or zero, based on the taxpayer’s modified adjusted gross income. SECURE 2.0 eliminates the MAGI tiers and makes the credit percentage 50 percent for all who don’t surpass the upper-income threshold. For example, if a married couple has $48,000 of income, and one of them makes a $2,000 contribution to a plan or IRA, the current credit of 10 percent equals a $200 tax credit. Under SECURE 2.0, that same couple would receive a 50 percent credit — $1,000.

SECURE 2.0 also incentivizes small businesses to offer retirement plans, an employee benefit that is often difficult for small businesses to establish.The three-year small-business start-up credit is currently 50 percent of administrative costs, up to an annual cap that can be as much as $5,000. If a company with up to 100 employees starts a retirement plan and spends $3,000 per year administering it, the employer currently receives a $1,500 per year credit for three years. Under SECURE 2.0, that 50 percent credit would increase to 100 percent for employers with up to 50 employees, going from $1,500 to $3,000 in this example.

To illustrate the power of the additional credit based on contributions, assume that a 40-employee company makes $500 contributions for each of its employees. The contribution-based credit for that company over five years would total $70,000 — $20,000 in each of the first two years, $15,000 in the third year, $10,000 in the fourth and $5,000 in the fifth. This is a powerful incentive that helps both the small business itself and of course its employees.

SECURE 2.0 allows student loan payments to be treated as elective deferrals for purposes of matching contributions. Under the bill, an employer would be permitted to make matching student loan contributions under 401(k) and 403(b) plans. This addresses a problem facing millions of employees who are so buried in student debt that they cannot afford to make retirement contributions and thus lose out on matching contributions offered by their employer. For example, if an employer provides a 50 percent match and an employee makes student loan payments of $1,000, the employer would make a $500 contribution to the plan on behalf of that employee.

There are a whole host of other provisions. For example, the bill would help part-time employees become eligible to participate in their employer’s retirement plan, addressing a key concern under today’s rules. Also, the bill would help our nation’s military spouses become covered by retirement plans despite having to move so much to support their spouses. And the bill establishes a lost-and-found registry to help individuals find retirement benefits that they have earned but lost track of.

With bipartisan cooperation toward solving problems seeming impossible to find, the SECURE 2.0 bill represents important progress that benefits working families across the country. The Senate has its own version making its way through the legislative process. Those following these bills closely expect that these bills will be combined and probably included in a broader legislative package.

Regardless of how it comes to be, let’s hope that lawmakers continue to work together on such a critical issue as financial empowerment for everyday Americans.
Read More

North Carolina flag

North Carolina flag

Gerrymandering is Dumb. Just Look at North Carolina.

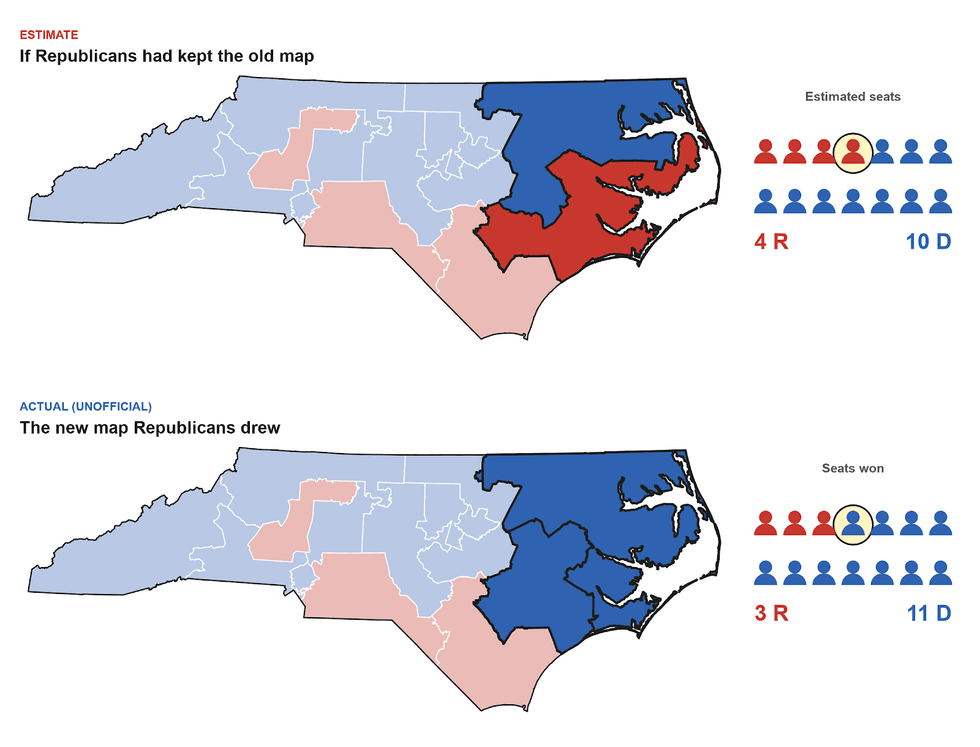
Ahead of the 2026 midterms, North Carolina Republicans redrew the state's congressional map in hopes of picking up another House seat. With every precinct reporting, the plan appears to have backfired.

By IVN's estimates, had Republicans kept the old map, they likely would have won one more seat than they did.

Keep ReadingShow less
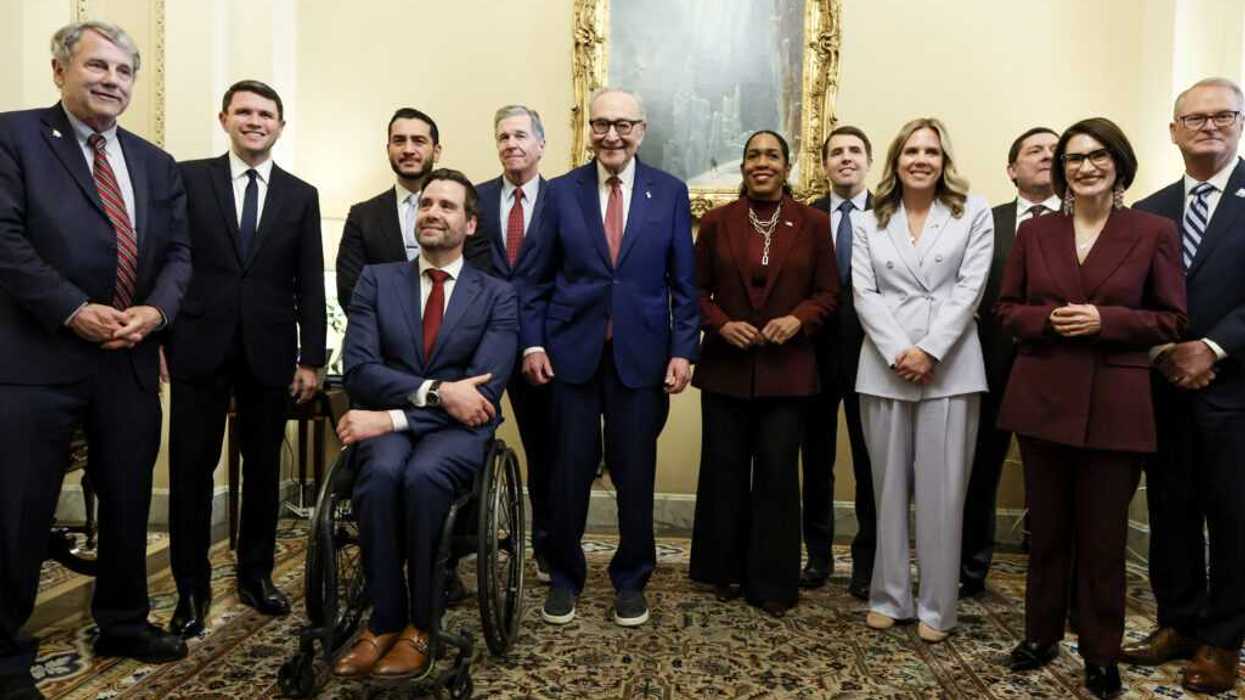
Newly elected Democratic Senators in his office in the U. S Capitol Building

U.S. Senate Minority Leader Chuck Schumer poses for a photo with newly elected Democratic Senators in his office in the U. S Capitol Building on Nov. 9, 2026, in Washington, D.C. Schumer posed for a photo with U.S. Sen.-elect Sherrod Brown, U.S. Sen.-elect James Talarico, U.S. Sen.-elect Abdul El-Sayed, U.S. Sen.-elect Josh Turek, U.S. Sen.-elect Roy Cooper, U.S.

Getty Images

Democrats need to level set with voters

It’s been two weeks, but many Americans are still reveling in the Democratic tsunami that swept the country on Election Day, brimming with excitement, teeming with hope for the future, and gloating from the ass-whooping Republicans just took.

After 10 long years of Donald Trump’s brute dominance over our political system— whether he was in office or lurking menacingly outside of it — MAGA, the nativist, nationalist, nihilistic movement he created, was finally beaten back. And not just in the expected places — but on new frontiers like Texas, Mississippi and South Carolina.

Keep ReadingShow less
two cars on a highway
Cars drive on a highway next to a river

Why Your Town’s Roads Run Through Washington: Unpacking Transportation Infrastructure Funding

Introduction

Access to reliable transportation is a critical part of most Americans’ daily lives. In 2022, Americans took an average of 2.28 trips per day, traveling 28.55 miles on average — figures including every mode of transportation and every purpose, for the full population. However, little attention is paid to transportation infrastructure until there are obvious problems like potholes or broken sidewalks linked to sharp decreases in road safety and quality of life for nearby residents. Given widespread reliance on transportation infrastructure makes examination of the governance structures underpinning its funding an important area of consideration.

Process-Shaping Priorities and the Federal Level

At the federal level, transportation infrastructure is primarily governed by the United States Department of Transportation (USDOT), an executive branch agency split into nine main operating administrations overseeing a specific part of the national transit system. USDOT then uses this oversight to distribute federal funding and ensure that individual transit outlets comply with national policy and safety standards. Distributed federal funding is drawn from the Highway Trust Fund, a dedicated federal fund financed through taxes on gas and other transportation costs, and distributed to states through formula-based approaches or competitive grant programs based on spending caps established by Congress. While federal funding plays an important role in transportation infrastructure, it only represents one-quarter of all public spending on roads and highways. The remaining three-quarters of long-term financing and associated maintenance is provided by state and local governments.

Keep ReadingShow less
Capitol Building in Washington, DC
white concrete building under blue sky during daytime

The Public Is Demanding Ethics Reform. Will Congress Listen?

At the end of the 2026 midterm elections, “corruption” emerged as a central issue in the campaign. The public outrage had been building for years. In a September 2026 Gallup poll, 89 percent of Americans agreed that corruption is “widespread throughout the government,” an all-time high. Allegations that members of Congress use insider information for stock trading have become a common belief. Additionally, a raft of sexual harassment and sexual assault scandals has shed light on the inadequate protections in place for congressional employees. As the 120th Congress convenes in January, Congress must respond to this national cry for ethics reform in the legislative and executive branches.

Historically, Congress has always needed a scandal to act. The Honest Government and Open Leadership Act of 2007 – famously proclaimed by Speaker Nancy Pelosi as an act to “drain the swamp” – was passed as a result of the lobbyist Jack Abramoff scandal involving illegal gifts and favors to members of Congress. It appears the swamp was harder to drain than anticipated.

Keep ReadingShow less