Skip to content
Search

Latest Stories

Follow Us:
Top Stories

Why the Tri-Merge System is Vital for Fair Homeownership

Opinion

Why the Tri-Merge System is Vital for Fair Homeownership
white house under maple trees
Photo by Scott Webb on Unsplash

For generations, home ownership has been part of the very definition of capturing the American dream. First-time buyers face a process that can be both exciting and daunting—the right home, in the right community, and with the right financing.

As housing costs continue to rise and first-time home purchases are being delayed more than ever, securing a mortgage at a competitive rate for a homebuyer is vital to making home ownership possible, which underscores the need for an accurate and comprehensive way to analyze borrowers’ creditworthiness.


Unfortunately, nearly 1 in 10 potential homebuyers are denied a mortgage when they apply, and that number is considerably higher for young adults, lower-income individuals, and minority borrowers. For example, Hispanic applicants are denied conventional mortgage financing at more than twice the rate of non-Hispanic white applicants, even when income and credit factors are similar, resulting in Hispanic families’ homeownership rate well below the national average. This tragedy is a reality for too many American families across all demographic groups.

Homeownership builds equity and stability. It ties families to their neighborhoods and strengthens local economies. Undermining access to credit means undermining that foundation, and we must continue to find ways to help correct these inequities.

With 61% of Americans “highly concerned” about housing costs, according to a recent Pew Research Center survey, we as a nation need to explore the barriers that may limit financial prosperity and home ownership. In particular, it is imperative to ensure fair access to credit for all Americans, including those in the working class and from underserved communities.

One system that we know works is the tri-merge credit reporting model, so-named because it combines data from all three major credit bureaus to determine a borrower’s creditworthiness.

A more complete profile is helpful for millions of potential borrowers building credit for the first time. Credit histories can be fragmented. Some may have credit cards or auto loans reported to only one bureau. Others pay rent or utilities faithfully, but those payments may appear inconsistently across the system. The tri-merge model fills those gaps, rewards responsibility, and helps families qualify for affordable credit in an impartial manner that reflects their true record, not one that can easily miss important elements.

However, some are now proposing eliminating the safeguard provided by the tri-merge model in favor of a “bi-merge” or “single-pull” model that uses credit reports from two or even just one credit reporting bureau.

But a less comprehensive report would create blind spots that disproportionately harm working-class and minority borrowers. Millions could see their credit scores misrepresented and mortgage applications denied because of missing or outdated data. Fewer families would qualify for home loans that are in fact within their reach, creating an unnecessary obstacle to the dream of ownership.

Given these realities, it is encouraging to see leaders at the Federal Housing Finance Agency (FHFA) reaffirm their commitment to maintaining the tri-merge standard. Ultimately, data-driven fairness and fiscal prudence can go hand in hand and align with FHFA’s stated goal of empowering more Americans.

Still, many borrowers can relate to being frustrated by mistakes or inaccuracies in past credit reports. Yet while there may be compelling reasons to adjust some elements of the reporting process, those reasons are separate from the question of the larger system and can be addressed in much more targeted and effective ways.

There certainly is room to improve policy related to housing, construction, and finance to benefit more Americans. Simplifying for the sake of appearances may feel appealing in Washington, but in practice, it could harm millions of responsible borrowers ' access to credit.

The tri-merge system might sound technical at first, but understanding its practical benefits reveals it as a quiet success story that has enabled more Americans from diverse backgrounds to access credit. Maintaining the pillar of credit access should be paramount to a successful policy that benefits Americans across the board.

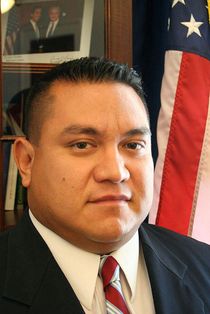
Mario H. Lopez is the President of the Hispanic Leadership Fund, a public policy advocacy organization that promotes liberty, opportunity, and prosperity for all.
Read More

 Dollar Bill Sticking Out of Piggy Bank on Yellow Background

A federal court sided with LAHSA, but LA nonprofits are still fronting millions to deliver government-funded homeless and DV services. Time to fix this.

Javier Zayas Photography/Getty Images

When Nonprofits Become the Bank for Government

It is a victory for Los Angeles in LAHSA v. Trump et al. that a federal court has temporarily halted the U.S. Department of Housing and Urban Development's suspension of the Los Angeles Homeless Services Authority and ordered HUD to execute already-awarded 2025 grants. The court found that HUD's action was arbitrary and unlawful, restoring LAHSA's role as the regional Continuum of Care applicant and protecting critical federal homelessness resources.

That is good news for Los Angeles.

Keep ReadingShow less
Construction worker


Low angle view of male construction workers framing a new house

Getty Images

Latino Workers Are the Backbone of America — But Inequities Persist

WASHINGTON — As the nation pauses today to mark Labor Day 2026, a glaring spotlight is shining on the massive economic influence, historical legacy, and evolving challenges of the Latino labor force. Once relegated to the margins of the broader American labor narrative, Latino workers are stepping into the national conversation as the indisputable backbone of the modern United States economy.

According to recent findings from the U.S. Bureau of Labor Statistics (BLS), the overall labor market has shown unexpected strength, with a stable baseline keeping the Hispanic and Latino unemployment rate hovering around 4.8%. While this reflects a significant drop from the 5.3% peak recorded a year ago, advocacy groups argue that the metrics mask deeper inequalities that holiday celebrations tend to overlook.

Keep ReadingShow less
US $1 dollar bill in mid air melting, red gradated background

From $215B to $7.14T: how outbound investment, falling labor share, and rising corporate profits reveal trickle-down economics' core flaw.

PM Images/Getty Images

Trickle-Down-Economics was Doomed from Day-One; yet Defended to Present-Day

By 1972, U.S. direct investments abroad amounted to $94.0 billion. This was two years prior to the development of the Laffer Curve in 1974 by American economist Arthur Laffer, famously sketched on a restaurant napkin during a dinner meeting in Washington, D.C. Therefore, the writing was on the wall regarding the vulnerability of Trickle-down economics, years prior to Reagan’s Economic Recovery Tax Act (ERTA) of 1981.

Trickle-down economics fails primarily because outbound foreign direct investment (FDI) allows corporations and wealthy individuals to invest tax-cut windfall profits globally rather than domestically. The theory of Trickle-down economics predicted that lowering taxes on businesses and high earners will stimulate local capital accumulation, leading to domestic business expansion, job creation, and wage growth for everyone. However, in a highly globalized economy, capital is hyper-mobile. Instead of filtering downward into the domestic economy, these untaxed or low-tax profits frequently exit the country entirely.

Keep ReadingShow less
An American & Canadian flag waving in the wind

An American & Canadian flag waving in the wind

Getty Images

Just the Facts: What’s Changed in U.S.–Canada Tariffs Since March 2025

The Fulcrum strives to approach news stories with an open mind and a spirit of inquiry, presenting our readers with a broad spectrum of viewpoints through diligent research and critical thinking. As best we can, remove personal bias from our reporting and seek a variety of perspectives in both our newsgathering and the selection of opinion pieces. However, before our readers can analyze varying viewpoints, they must have the facts.

In March of 2025, I wrote a column for The Fulcrum, Just the Facts: Canadian Tariffs, that set out to do something simple: strip away the rhetoric and explain, plainly, what tariffs between the United States and Canada actually were, what each country imposed, and why. That piece went on to become the most‑read article in Fulcrum history — more than 300,000 readers — because people were hungry for clarity in a debate that had become clouded by politics, slogans, and selective memory.

Keep ReadingShow less