IVN is joined by Nate Allen, founder and Executive Director of Utah Approves, to discuss Approval Voting and his perspective on changing the incentives of our elections.
Podcast: Seeking approval in Utah
IVN is joined by Nate Allen, founder and Executive Director of Utah Approves, to discuss Approval Voting and his perspective on changing the incentives of our elections.

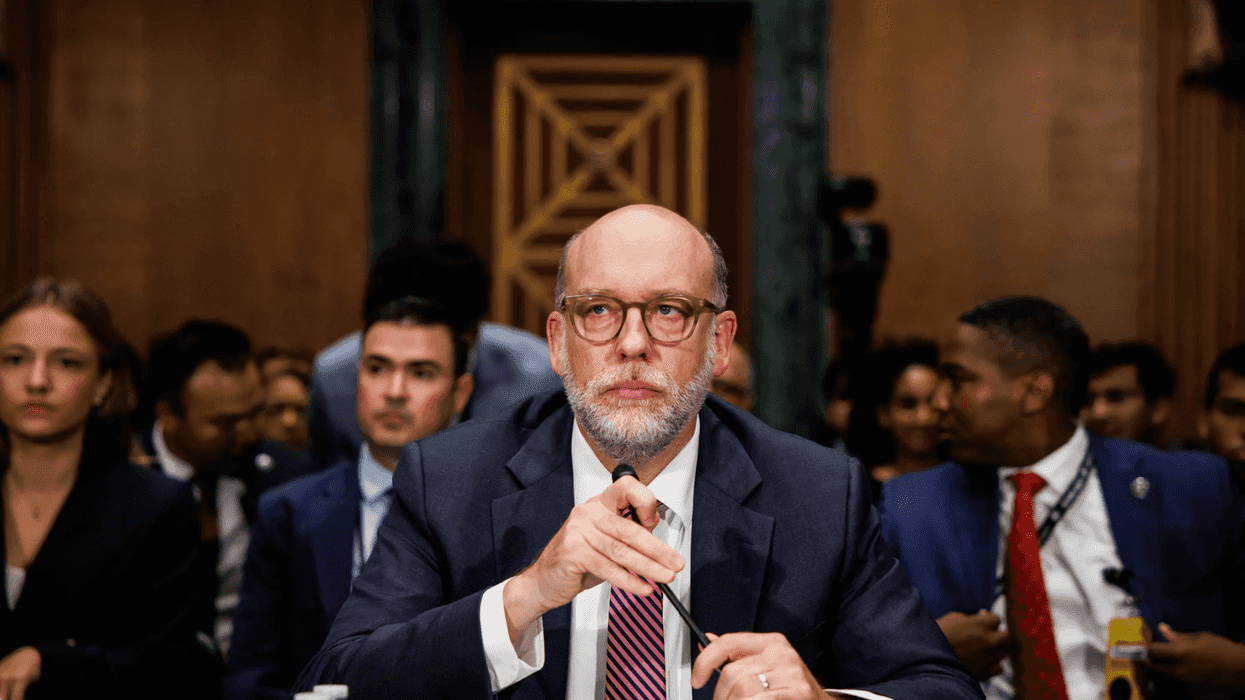
Russell Vought, the acting director of the Consumer Financial Protection Bureau, testified before the Senate Committee on Banking, Housing and Urban Affairs in July.
In mid-July testimony before Congress, Russell Vought boasted that, as the acting head of the Consumer Financial Protection Bureau, he’d refashioned the agency’s approach to pursuing banks and other financial companies accused of exploiting Americans — the role Congress had created for the agency after the 2008 economic crash.
Vought had spent the first 18 months of the new Trump administration trying to dismantle the bureau, much as he and other appointees had done with the U.S. Agency for International Development. At CFPB, he’d ordered mass layoffs, tried to choke off the bureau’s funding and ended the lease on its headquarters, attempting to make good on his vow to put civil servants “in trauma.” But federal courts blocked Vought’s efforts to close the CFPB, with a judge at one point saying the administration had acted with “complete disregard” for Congress.
So Vought, who is one of President Donald Trump’s top advisers, switched tactics: If there had to be a watchdog, theirs would be more of a golden retriever, friendlier to industry and less aggressive. Vought had accused the bureau of “thuggery” in the past, and said the “new” CFPB would focus on deregulation, embrace “humility” and adopt a “collaborative approach” to its dealings with companies that harm consumers.
As evidence of the success of this new approach, Vought singled out one company by name in his testimony, a buzzy startup called Bilt. The company, which offers credit cards used to make rent and mortgage payments, had fumbled a critical transition, leading to confusion and financial stress for its customers. In the past, the CFPB might’ve deployed examiners to ensure that every consumer harmed got relief, investigated Bilt’s technology platforms for potential flaws, questioned its third-party contractors or issued subpoenas — with the goal of finding the root causes of whatever went wrong and preventing it from happening again.
The Trump-era CFPB took a different tack. “We reached out to the company,” Vought told Congress, “and before it got to the adversarial part of the process, they were able to fix their issues.” The CFPB even posted a feel-good statement on its website, touting its new approach and telling consumers that information provided by Bilt “appears to show” the firm was “back on track.”
Yet two weeks after Vought’s testimony, Bilt failed customers again. This time, Bilt cardholders received mistaken debt collection notices and saw their credit scores go down as a result, sparking more embarrassing news stories and angry complaints. It was Bilt’s second fiasco in six months, and as its customers scrambled to understand what had gone wrong, the CFPB was nowhere to be found.
The Bilt controversy offered an early test of CFPB’s new approach, and the results suggest that an ask-nicely strategy to consumer protection isn’t likely to protect consumers. What’s more, current and former CFPB officials say the bureau could’ve caught the issues that caused the second of Bilt’s two screw-ups had the previous playbook still been in use.
ProPublica sent the CFPB a detailed set of questions about its handling of the Bilt complaints and what actions it took to protect consumers and prevent future problems. The bureau did not respond to any questions or requests for comment.
The whole episode drives at a bigger question, according to consumer advocates and current and former CFPB employees: If the Trump administration can’t eliminate the CFPB, what will become of it in the hands of Trump officials, such as Vought, who have long believed the agency is unnecessary? (Vought termed out as acting director in early August but remains a senior adviser. The administration’s nominee for full-time director, Brian Johnson, is an executive at Capital One bank and a former CFPB appointee. At his confirmation hearing, Johnson said he could not think of a single decision that he disagreed with made by Vought at the CFPB.)
“What we saw Vought do with Bilt is innovative — and I don’t mean that as a compliment,” said Mike Pierce, a former CFPB official who runs the consumer advocacy group Protect Borrowers, which has criticized Vought’s tenure at the bureau.
Bilt’s business rests on a simple premise: Consumers should build credit and earn rewards for what’s typically their single biggest expense — their rent or mortgage payment. “Prior to Bilt, that payment didn’t build anyone’s credit history, which is crazy,” Bilt co-founder Ankur Jain said in March. Jain added that it was “silly that you can earn rewards buying a round of drinks at a bar, but not paying your rent every month.”
Founded in 2021, Bilt is one of the hottest startups in the personal finance industry. Bilt says it has 7 million customers and has raised nearly $1 billion in venture capital investments, at a $10.75 billion valuation. Investors include private equity giant Blackstone, the Ontario Teachers’ Pension Plan and a venture capital fund chaired by former American Express CEO Kenneth Chenault.
Forbes estimates Jain’s wealth at $3.4 billion. People magazine published exclusive photos of Jain’s 2024 wedding to Erika Hammond, a former WWE wrestler and cast member on the upcoming season of “The Real Housewives of New York City.” The event took place near the Great Pyramid of Giza; one photo shows the couple kissing at sunset with the Sphinx and pyramids in the background.
Earlier this year, Bilt suffered a serious crisis. The startup had signed a seven-year partnership with Wells Fargo to offer Bilt-branded credit cards that could be used to pay rent. Under its deal with Bilt, Wells Fargo agreed to absorb processing fees associated with rent transactions and make payments to Bilt because it saw the partnership as a way to attract new customers who might one day seek a mortgage from Wells Fargo, according to The Wall Street Journal.
But revenue fell short of Wells Fargo’s projections, and the bank was losing so much money — as much as $10 million a month, the Journal reported — that it ended its partnership with Bilt four years early. (A Bilt spokesperson said at the time that the Journal’s reporting was “an inaccurate representation” of the Wells Fargo partnership.)
Bilt co-founder Ankur Jain attended the Bilt Rewards x Wells Fargo launch party in March 2022. Jared Siskin/Patrick McMullan via Getty Images
In February, Bilt relaunched its credit cards with new financial partners. But the rollout of “Bilt 2.0,” as the company called it, was a debacle.
Customers said their rent payments were paid late, double-charged or not paid at all. Credit limits had been lowered from one card to the next. Their cards were inexplicably frozen. “This unexpected double charge has caused significant inconvenience and financial distress,” one Bilt customer wrote to the CFPB in February after Bilt paid her rent twice in the same month. (A Bilt spokesperson said, “As soon as we were made aware of this issue, we resolved it and made the member whole.”)
Bilt’s customer support department struggled to keep up as tens of thousands of messages poured in. Customers fumed that they were unable to bypass chatbots and reach a human being for help. They also bombarded the CFPB’s website with complaints, which included accounts of how Bilt’s AI support system gave information that was “completely wrong” and “demonstrably … false.” (In a statement at the time, Bilt said its new card had “attracted unexpectedly high demand, and some of our members experienced gaps in service that are simply unacceptable to us.” The company told ProPublica it resolved all problems related to the new cards “months ago.”)
In March, the consumer group Protect Borrowers sent a letter to the CFPB, demanding that the bureau’s supervision or enforcement divisions take “immediate action.” Sen. Elizabeth Warren, D-Mass., wrote to Bilt, pointing out a 1,300% increase in complaints about the company submitted to the CFPB in February and seeking answers about the Bilt 2.0 transition. Warren also said that Bilt’s practice of immediately debiting rent payments may have run afoul of the 2009 Credit Card Accountability Responsibility and Disclosure Act’s disclosure requirements for credit cards. A Bilt spokesperson said Warren’s assertions were “incorrect.”
It’s common for lawmakers and advocacy groups to fire off outraged letters about a company’s alleged wrongdoing.
The strange part is what the CFPB, then led by Vought, chose to do about it.
The law that established the CFPB, the Dodd-Frank Act of 2010, envisioned two tracks for the bureau’s work.
On the supervision track, CFPB employees would periodically visit banks and other financial institutions to monitor their business practices and ensure compliance with the law. Supervision would be confidential, giving companies the ability to adjust their operations without public scrutiny. Contrary to Vought’s accusations, current and former CFPB staffers say the traditional supervision process has long been collaborative and nonpublic. Congress designed it that way when it wrote the law.
Supervision could examine the past or look in real time. In one notable instance, when two federal student loan servicers exited the industry in 2021, the bureau’s supervision division chose to proactively monitor the transition of more than 9 million borrowers’ accounts to new servicers. Bureau staffers caught problems mid-transfer, from inaccurate due dates to botched repayment schedules, and directed the companies to fix them. It later published a recap of what the CFPB did as well as a set of tips so that the rest of the industry could avoid the same mistakes.
On the enforcement track, CFPB lawyers would file lawsuits against or pursue consent decrees — binding settlements that courts can enforce — with companies that allegedly broke the law. By their nature, lawsuits and settlements are public, but the enforcement division didn’t speak publicly about its actions apart from its filings.
The Trump-era CFPB took neither of these tracks in response to Bilt’s first incident. A senior political appointee and Vought aide, Victoria Dorfman, took the lead in contacting Bilt and asking for information about the consumer complaints, according to a person familiar with the interactions who requested anonymity to share confidential communications. Dorfman was joined by Elie Greenbaum, another Vought adviser, and Deborah Morris, the deputy enforcement director. Having political appointees lead this process, instead of nonpartisan career executives and subject-matter experts, was “abnormal” for the CFPB “but is becoming normal” under the Trump administration, a current CFPB staffer told ProPublica.
Dorfman, Greenbaum and Morris met with Bilt’s executives, who explained how they were fixing the problems and supplied data to the bureau about the company’s customer communications and efforts to resolve problems. When Bilt assured the bureau it had fixed the issues, CFPB officials appear to have taken those assurances at face value, issuing a celebratory press release on the bureau’s website.
But it was what the press release said, or didn’t, that alarmed some current and former CFPB officials. Nowhere does it mention whether the bureau dispatched examiners to help locate the root of Bilt’s problems, as it would have done in the past, or whether it conducted its own audit of Bilt data to ensure every harmed consumer got relief.
Indeed, the CFPB’s statement stressed that the bureau did not open an investigation. Nor did it craft a consent decree or enforceable pledge to ensure compliance. Documentation provided by Bilt, the bureau said, “appears to show” that the company had fixed its problems and that its systems were “back on track.”
Austin Hinkle, a former supervision lawyer and section chief at the CFPB, said it’s easy for a company to identify a population of customers who were harmed, issue an apology and get them relief, as Bilt did.
Understanding what caused the issue is more complicated — and arguably just as important. In a situation like Bilt’s, Hinkle said, CFPB examiners would normally conduct a root-cause analysis, asking, for instance, which system led to the late or double-charged rent payments and why had it failed. Financial technology companies often rely on third-party processors and banks, Hinkle said, so the bureau’s investigators would also scrutinize what outside firms Bilt uses and what the communications have been with those firms.
There’s none of that depth in the CFPB’s statement, Hinkle said. “The press release just looks like they’re providing air cover for the company without directing real fixes or systematic changes.”
The lighter touch appears, so far, to be a hallmark of the Vought-era bureau. It has brought just one enforcement action since Trump took office, which ended with a consent decree and a civil penalty of $1, while dismissing or resolving dozens of cases brought during previous administrations. A CFPB supervisor warned her subordinates that they would face “most unpleasant” consequences if they were too aggressive in their work, Reuters reported. Recently, the bureau announced it would no longer include narratives in consumer complaints that appear in the CFPB’s public database.
Meanwhile, a current CFPB staffer told ProPublica that the number of policy attorneys, who help direct supervision work and identify violations of law, had shrunk from typically between 40 and 50 lawyers down to five. The staffer said that examiners were no longer allowed to access the primary source level data and could only “check the checker now,” meaning they must rely on a company’s own findings. They also faced pressure to finish examinations as fast as possible, given only three weeks to complete their work when they used to have eight weeks.
The staffer added that, as far as they knew, the first time that front-line staffers on the supervision and enforcement tracks heard of CFPB’s handling of the Bilt case was either the public statement or when Vought mentioned Bilt in his Capitol Hill testimony.
Pierce, the Protect Borrowers director, said he viewed CFPB’s treatment of Bilt as an indication that the bureau had embraced a mindset similar to what Ronald Reagan’s presidency was known for: a wholesale deregulatory approach meant to strip away regulations and oversight of companies large and small.
“It’s taking the government’s supervision and enforcement tools and figuring out how you can use them the way the Reaganites used them,” Pierce said.
Roughly two weeks after Vought’s testimony, Bilt customer Jordan Carey, a 30-year-old who works in the hospitality industry, received an alert from Credit Karma, the credit-monitoring service. His credit score had dropped 50 points in a single day. The news “sent me into a panic,” Carey said. He had stellar credit and paid off his Bilt credit card the day charges were posted. “I was thinking there is no way this is real,” he said.
Carey dug deeper and saw that the hit to his score had happened after a debt collector, Tate and Kirlin, reported a supposed long-overdue payment. And when he looked at the collections notice, he saw it listed Bilt as the cause of the error.
When he alerted Bilt’s customer service to the problem, he said, “they were not aware of the issue [and] I’m pretty sure I was one of the very first people to report it.” A Bilt customer service agent initially laid the blame with Wells Fargo and told Carey to contact the bank for help. But when he posted on Reddit about his experience, he got a different response from Bilt about the source of the problem, blaming a different banking partner. He also heard from almost a dozen other people who said they had the same issue.
Nearly 1,900 of Bilt’s customers received mistaken notices from a debt collector that said they owed hundreds or even thousands of dollars in unpaid credit card balances. On Reddit, people wrote about receiving one or multiple false collections notices, including, in one case, as the cardholder was closing on a new house.
Hinkle, the former CFPB section chief, said the more recent Bilt problem was the kind of situation the CFPB’s previous oversight model could’ve prevented or identified more quickly, instead of customers discovering the problem and self-reporting it. “The fact that there’s a seemingly related problem popping up now suggests to me that the normal supervisory process didn’t work here,” he said.
The CFPB has not made a public statement since Bilt’s second breakdown.
Bilt, for its part, said the issue had to do with an earlier iteration of its credit cards that had stopped accepting customers. The company said it alerted the collection agency in question as well as the credit bureaus to the mistake. It also awarded customers an extra 2,500 points for their trouble, worth between $25 and $50. “We held the agency accountable, made things right for every customer involved, ensured each was notified directly and provided direct customer support along with courtesy Bilt Points,” a spokesman said.
Carey said his credit score had been restored within a few days but was unimpressed by the free points; 10,000, or about $100 to $200, would have felt more appropriate. “This is a multibillion-dollar company,” he said. “They can afford it.”
The Trump Administration’s Plan for Protecting Consumers? Politely Ask Companies to Behave. was originally published by ProPublica and is republished with permission.
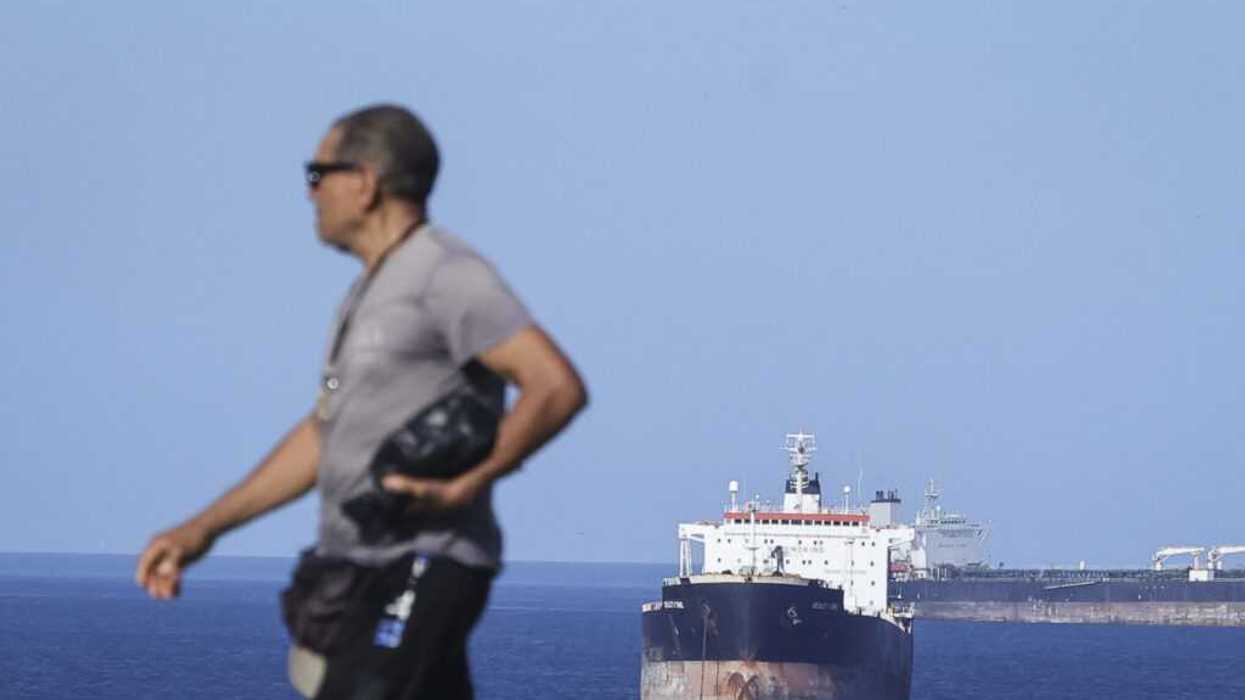
man walks near the Punta Cardon refinery, on Jan. 23, 2026. Venezuela has the largest oil reserves in the world with an estimated 303 billion barrels.
So, it was a war for oil after all.
On social media Friday, President Trump announced that the United States and Venezuela have struck an agreement for “THE BIGGEST OIL DEAL IN WORLD HISTORY.”
The whole thing is appalling, starting with the all-caps.
I have no love for the Venezuelan regime, run by, in Trump’s words, “the Highly Respected Interim President” Delcy Rodriguez. But this is a “deal” that Rodriguez couldn’t refuse. We invaded her country, abducted her criminal-dictator boss, Nicolás Maduro, and made her our satrap.
According to the Wall Street Journal, Venezuela and the U.S. will work through two intermediaries to get the oil flowing. The Venezuelan partner is Alejandro Betancourt, head of North American Blue Energy Partners. He’s been investigated, though not charged, for money laundering in Spain and Switzerland. He’s also one of the most famous “Bolichicos,” a nickname for the young businessmen who’ve gotten rich from their ties to the socialist, murderous, criminal dictatorship (it’s a portmanteau of “Bolivarian” and “Bourgeois”).
And who is the American partner? Well, the Pentagon, of course. Trump couldn’t get American oil companies to invest billions in Venezuela’s decrepit oil industry. (At a White House meeting in January, Darren Woods, the chief executive of Exxon Mobil infuriated the president by describing Venezuela as “un-investable.”) So, the commander in chief tapped the Pentagon’s Office of Strategic Capital to take a 35% stake in Betancourt’s firm, securing the right to buy 20% of all production “at cost.” Created in 2022, the OSC was intended to use loans and loan guarantees to help develop vital industries. Now, it’s the primary backer of the “history’s biggest oil deal.”
We’ll see how legal this is. You can be sure someone will be going to court over it. After all, the U.S. government will be working with a criminal regime, under implausible statutory authority, to buy oil at below-market rates while undermining our own oil producers.
I won’t shed many tears for the oil companies, even if the administration pulls this off. Then again, I don’t think they will, at least not any time soon. Trump boasts that this will help lower gas prices. Maybe. Someday. But even this scheme’s biggest boosters acknowledge that if it all goes swell, it will still take years to get the relevant oil fields producing, and years to retrofit American refineries to take Venezuela’s subpar oil. So, if Trump thinks prices at the pump are coming down before the midterms, or even during his presidency, he should think again.
But my primary objections to this imperial smash-and-grab are constitutional and moral. The constitutional problem is pretty straightforward. Trump lied to Congress and to the public about this scheme from the get-go. He claimed Operation Absolute Resolve was a mission by law enforcement to capture Nicolás Maduro. The same indictment for Maduro and his wife included members of the regime. We left them in place, because law enforcement was a pretext.
Roughly 11 hours after apprehending Maduro, Trump boasted that the U.S. was going to “run the country” by working with the criminal regime. Did Congress authorize that? Congress definitely didn’t authorize the Pentagon to get into the oil business.
Trump has a long, long history of claiming that America should “take the oil” from countries we go to war with. And months before this deal, he bragged that oil revenue from Venezuela has “paid for the attack many times over…. I always used to say, ‘To the victor belong the spoils.’ ”
Ironically, this phrase comes from a defense of the corrupt spoils system in U.S. politics, not some time-(dis)honored rule of war.
The Constitution does not empower the president to unilaterally launch wars, even brief ones, for the purpose of seizing or extorting a nation’s wealth. It’s worth noting that although the fighting in Venezuela was brief, the Iran war is dragging on. And that was his plan for Iran too.
“If I had my choice, what would I like to do? Take the oil. Because it’s there for the taking,” Trump told reporters in April. He also posted on social media: “With a little more time, we can easily OPEN THE HORMUZ STRAIT, TAKE THE OIL, & MAKE A FORTUNE.”
Then there’s the whole democracy thing. The administration vowed to restore Venezuelan democracy, eventually. We were supposed to be liberators bringing Venezuela freedom, according to the White House. Now, we’ve signed a “century-long” agreement with a corrupt, unelected, murderous regime. Do you think Trump is going to be in any kind of hurry to bring democracy to Venezuela now?
Jonah Goldberg is editor-in-chief of The Dispatch and the host of The Remnant podcast. His Twitter handle is @JonahDispatch.

Teal shoes are displayed outside Naval Medical Center Portsmouth in April 2018 as part of Sexual Assault Awareness and Prevention Month.
When Mayra Diaz opened the door of her Army barracks room in 2022, she didn’t realize it was the beginning of the end of her military career.
She had never met the soldier standing in front of her, Sgt. Greville Clarke. She didn’t know he had sexually assaulted three other women on base over the past 15 months, including one he threatened at knifepoint.
Diaz remembers Clarke lifting his uniform top to show he was armed with a handgun. She can’t recall much else after he forced his way into the room, where she lived alone, and assaulted her. It wasn’t until a full day later that a friend found her on the floor with fresh bruises on her neck. Clarke went on to attack a fifth woman before he was finally caught.
In April 2025, Clarke was convicted in a court martial at Fort Hood, Texas, on 29 specifications—including rape, attempted premeditated murder, and kidnapping—for attacking five women. Not long after he was given a life sentence, in September, he died of an apparent suicide in his cell at the Army’s prison in Fort Leavenworth, Kansas, according to Stars & Stripes.
Meanwhile, Diaz soured on her dream to serve until retirement, leaving the Army just two years after she joined.
“I wanted to make it far in the military,” she said. “But I couldn’t stand being in the same uniform.”
This year, Diaz filed a claim against the Army, accusing Fort Hood leadership of failing to provide a safe environment on base. Historically, lawsuits from service members against the military have faced a near-insurmountable barrier: a legal principle known as the Feres doctrine, which bars troops from suing the government for harms incurred during military service.
A new bill in Congress could change that. The Military Sexual Trauma Accountability Act, which has bipartisan support, would allow service members to sue the military for sexual misconduct and related issues, such as failing to investigate reports of misconduct or for negligence in creating an unsafe environment where sexual assault or harassment is allowed to fester.
In 2024, the military received more than 8,000 reports of sexual assault, the majority allegedly committed by service members. That’s a decline of about 4% from the previous year. But researchers with Brown University’s Costs of War project estimate that the total number of sexual assault cases is two to four times higher than the reported cases.
“Accountability doesn’t end with the perpetrator being found guilty and going to jail,” said Josh Connolly, senior vice president of Protect Our Defenders, a nonprofit group that works to end sexual misconduct in the military.
“If the military was on the hook for millions, if not billions, of dollars,” he said, “I think that would create an incentive for the military to take this more seriously.”
When Diaz joined the Army in 2021, she was excited to see the world beyond her hometown of Fresno, California.
“I wanted to go to Germany. I wanted to go to Korea,” she said. “I wanted to do all that the military had to offer.”
Her first duty station, however, was closer to home. At basic training, Diaz learned that she would be stationed in Texas at one of the Army’s largest bases.
“Be careful,” a drill sergeant warned, ominously. “It’s Fort Hood.”
Roughly two years earlier, the dismembered remains of Spc. Vanessa Guillén had been found near a river not far from the base next to Killeen. A fellow soldier had murdered Guillén inside an armory at Fort Hood, not long after she confided to her mother that she was being sexually harassed. Guillén’s death spurred a public outcry for greater accountability and protection of women in the ranks, which led to changes in how the military prosecuted sexual misconduct cases.
But when Diaz reported to the base in 2022, she noticed that fellow soldiers still didn’t take rape and sexual harassment seriously. The culture of the Army apparently hadn’t changed much. After her own assault, for instance, a fellow soldier asked why she had opened her door.
“We’re talking about an institution that has had a tendency to blame victims,” Connolly said.
Diaz found some measure of justice within the military system when Clarke was arrested and convicted. But she still thinks the military could have done more to keep her safe. Army criminal investigators did not investigate Clarke’s first attack, and military police on base closed the case after DNA evidence proved inconclusive. But even after Clarke attacked two other women, none of Diaz’s leaders warned anyone in the barracks about the assaults, according to her legal claim.
“If we were warned properly, [then] maybe this wouldn’t have happened to me,” Diaz said. “They failed to take accountability for where they went wrong.”
Under the Federal Tort Claims Act, citizens can sue the government for negligence or wrongdoing. But Feres limits service members from bringing claims against the military for harms that are “incident to service.”
The principle, according to experts, is rooted in the idea that service members must accept some risk to join the armed forces, and that a lawsuit could undermine the military command structure. But advocates bristle at the persistent denial of claims from military sexual assault survivors due to Feres.
“What they’re saying is that being raped is somehow incident to your military service,” said Christine Dunn, Diaz’s lawyer. “Which is appalling.”
Although Feres has served for more than 70 years as a barrier to claims against the military, it hasn’t stopped some service members from trying. For decades, courts have cited Feres to dismiss most cases brought by service members against the government. But in recent years, Feres critics have sensed a shift.
In 2021, for example, the Supreme Court declined to hear a case from a West Point cadet who sued the Army for failing to keep her safe from being raped by a fellow cadet. The decision allowed the lower court’s decision to stand, which dismissed the cadet’s claim due to Feres. But Justice Clarence Thomas dissented.
“Under our precedent, if two Pentagon employees—one civilian and one a servicemember—are hit by a bus in the Pentagon parking lot and sue, it may be that only the civilian would have a chance to litigate his claim on the merits,” Thomas wrote, arguing that the Supreme Court should revisit the doctrine.
Then, two years later, the Ninth Circuit Court of Appeals agreed with a lower court’s decision on a sexual assault case against Air Force Gen. John Hyten that Feres did not apply because the assault could not be considered as “incident to [military] service.”
“It is not conceivable that his military duties would require him to sexually assault Plaintiff, or that such an assault would advance any conceivable military objective,” the lower court wrote.
The case settled out of court and the government paid the plaintiff, Col. Kathryn Spletstoser, nearly $1 million. It was the first known payment from the military in a sexual assault case against a service member.
That ruling could provide an opening to challenge the doctrine in court, said Dunn, Diaz’s lawyer. She also represents survivors in another high-profile case involving Dr. Blaine McGraw, a former gynecologist at Fort Hood and Tripler Army Medical Center in Hawaii, who is facing charges for allegedly abusing nearly 100 patients, many of whom he secretly recorded.
“When you have so many victims complaining about the exact same thing, it’s hard to argue there wasn’t some negligence,” Dunn said.
Dunn points out that Feres creates a parallel—and unequal—justice system. Both Army spouses and service members were victims of McGraw’s alleged abuse. But only the civilian spouses are able to sue the military.
“Feres has so long protected the institution and not the service member,” said Rita Graham, policy director at Service Women’s Action Network, which advocates for women in the military.
Military justice reform advocates argue that relying on courts to limit the Feres doctrine is a slow and inefficient way for survivors to get justice. They see a better path through legislation.
In 2019, Congress passed the SFC Richard Stayskal Military Medical Accountability Act, which carved out an exception to Feres for service members harmed due to negligence or wrongdoing in the military medical system.
The Military Sexual Trauma Accountability Act builds on that idea, allowing sexual misconduct survivors in the military to sue the government.
“Servicemembers give up a lot to defend this country, but they should not have to give up their right to hold the government accountable when its negligence contributes to sexual assault or harassment,” said Republican Sen. John Kennedy of Louisiana, a cosponsor of the bill with Democratic Sen. Jeanne Shaheen of New Hampshire.
Military justice reformists hailed the passage of the Military Medical Accountability Act, but implementation of the law has been anything but smooth. The law allowed service members to submit malpractice claims to the military, which are reviewed by military lawyers. But fewer than 10% of claims filed since 2020 have been approved, according to recent reporting from the military news site Task & Purpose. Even the bill’s namesake, Richard Stayskal, was denied his claim against the military for overlooking symptoms of Stage 4 lung cancer.
To avoid a similar fate, the new bill would allow sexual assault survivors to directly sue the government in civilian court, instead of filing a claim with the military.
“Just cleanly giving people the ability to go to court for an assault would be the best policy,” said Connolly, who advised lawmakers on the bill.
Survivors hope that, if passed, the bill would force the Pentagon to root out sexual misconduct in the ranks or face serious financial and reputational consequences.
“If the perpetrators are never held accountable, if the people that convince you not to really press charges aren’t held accountable, if you take it to court [martial] and they’re still not held accountable, well, then the military should be held accountable,” said Cairey Williams, a former soldier who said she had been sexually assaulted at all three bases where she was stationed after joining the Army in 2003.
“Until somebody is held accountable, it’s just going to keep going,” she said.
Ultimately, survivors and advocates say it isn’t about the money. Instead, they hope the threat of financial penalties will force the military to do more to prevent sexual assault and harassment for future generations of Americans who decide to serve.
“Regardless of them giving me money, not giving me money, I still have to live with what happened to me for the rest of my life,” Diaz said. “And as much as I could try, money can’t buy off the trauma that I go through now.”
Military Sexual Trauma Survivors Can’t Sue the Government. A New Bill Could Change That. was originally published by The War Horse, shared by The 19th, and is republished with permission.
Horizontal photo of a DEMOCRATIC PARTY FLAG with a stylized DONKEY with 3 white stars on blue top of donkey and two red feet. Flag is laying on top of a red, white, and blue American Flag.
Labels can be misleading and misused. The label "Centrist" is empowering because it signifies you are mainstream, not extreme, a place where all people can come together. To be labeled "Left" is to place you outside the mainstream, extreme; left connotes a kind of kookiness as well as—horror of horrors—Socialism.
But are the labels accurate? For most of the 20th century, the Democratic Party was, without question, the party that championed the working man, the average person—the people. But they were nevertheless firm capitalists—they were not Socialists.
All the actions government has taken to improve the opportunities and lives of working men and their families, the poor, and the elderly have been enacted by Democratic Congresses under Democratic Presidents. To name but a few of the highlights:
Workers - The National Labor Relations Act of 1935 guaranteed private-sector employees the right to organize into unions, engage in collective bargaining, and go on strike. It also prohibited unfair labor practices by employers. A Democrat-controlled Congress passed it under Democratic President FDR. That act was amended in 1947 by a Republican-controlled Congress over President Truman's veto to restrict union actions and create union unfair labor practices.
The Elderly: Social Security was passed in 1935 by the same Congress under President Roosevelt. Medicare was passed in 1965, again with both houses of Congress controlled by Democrats and Democratic President Johnson. A vocal campaigner against Medicare, on behalf of the AMA, was Ronald Reagan, who called it socialized medicine.
The Poor - Aid to Families with Dependent Children was another law that was passed in 1935, part of FDR's effort to have government help those in need and thus enable them to pursue their lives. The Food Stamp Act was passed in 1964, again by a Democratic-controlled Congress under President Johnson, part of his War on Poverty.
As a result of these laws, workers prospered and rose to become solid middle-class Americans. The elderly were more secure and independent. And the poor, while certainly still poor, gained a better standard of living and more stability. Because of their support of the worker against corporate interests and the poor, many Americans—Republicans—viewed them as "leftists."
In the 1980s, after the election of Ronald Reagan, some Democratic leaders felt that the Party needed to appeal to a broader base, and they coveted the money that flowed from corporations to the Republican Party. These Democrats formed the Democratic Leadership Council, which included Bill Clinton.
Under their influence, the Party's actions—if not its stated ideology—shifted to the Right. While still championing support for the poor, people of color, and workers, the support of industry interests was unmistakable. Whether it was Clinton's embrace of Free Trade Agreements, his signing of the Republican Congress's repeal of the Glass-Steagall Act (a depression-era regulation of banks), or Obama's lack of support for reinstating the Glass-Steagall Act after the 2008 stock market crash and resulting recession—clearly the Democratic Party was lending support to interests of industry that were against the interests of middle-class working Americans.
Now we are seeing a surge in the popularity of Democrats who are members of the Democratic Socialists of America (DSA), who champion the interests of the working man, the average person. And they are succeeding because, despite the label—"Socialist" or "left"—that "centrist" Democrats as well as MAGA Republicans apply to them, their words appeal to the mass of people who have been suffering for years under policies that take little account of their interests.
Seen in this historical light, who is "centrist" in terms of the Democratic Party? It is the Democratic DSA candidates, the Progressives, who are truly Democratic centrists. And it is the self-avowed centrists who, in terms of the Democratic Party, are right-wing.
When looking at the country as a whole, the Democratic Party is clearly left of the Republican Party—now more so than ever before—but does that mean it is leftist? In terms of our founding documents ... the Declaration of Independence and the Constitution ... the Democratic Party has been centrist in that the policies it promotes and has promoted mostly move the country closer to our founding principles. If the Democrats are considered "left," then our founding documents must be considered "left" as well.
I have argued that Democratic DSA candidates should resign from the DSA because the DSA's fundamental position is antagonistic to Democrats' fundamental beliefs and America's founding principles. It works for a "government and economy by and for the working class." That is not democracy, which is defined as government by and for all the people, not some subset. And that is not the belief of Bernie Sanders, Zohran Mamdani, Abdul El-Sayed, or most, if not all, of the other candidates who are members of the DSA. (See my article, "The Democratic Socialists of America Is Not What It Seems.")
A generation of Democrats has been conditioned to think of themselves as "centrists," Democrats in the mold of Bill Clinton and Barack Obama—great Americans, great Democrats, and fervent supporters of the people, but they tried to have their cake and eat it too. They got into bed with corporate America, and the result was the inevitable growth of corporate influence and interests in shaping Democratic policies.
This shift to the right must end. It has hurt the American people, especially the blue-collar worker, and it has hurt the Party. 50.1% of U.S households had incomes under $75,000 in 2022. If Democrats want to once again become the majority party, then these are the people, both urban and rural, that the Party must appeal to, in addition to suburban women and liberals of all stations. And these are the people who are the natural constituents of the Party. Yes, even the rural poor and middle class; they may traditionally vote Republican, but they will be natural Democratic voters once the Party gets beyond the culture labels. See my article, "Winning the Rural Vote: A New Approach for the Democratic Party."
Bottom line, the Democratic Party has always been, and should remain, a big tent, with its central goal being to give all people an equal opportunity to pursue their right to life, liberty, and happiness. Whether one is more conservative in their approach, you are still a Democrat. If you are more radical in your approach, you are still a Democrat. The main thing is that we all agree on the Party's mission to pursue that goal, and that all the Party's policies must support that goal and serve the people's interests. (See my article, "Can the Democratic Party Still Lead?")
We must return to the fundamentals of the Party, just as we must return to our founding principles as expressed in the Declaration of Independence, if America is to be saved from becoming an ever-increasing land of inequality rather than one of increasing equality. The Party must stand for, as Abraham Lincoln put it, "government of the people, by the people, and for the people."
Ronald L. Hirsch is a teacher, legal aid lawyer, survey researcher, nonprofit executive, consultant, composer, author, and volunteer. He is a graduate of Brown University and the University of Chicago Law School and the author of We Still Hold These Truths. Read more of his writing at www.PreservingAmericanValues.com