Basma Ahmad leaves her apartment in Arlington, Va., just after 7 a.m., walking a few blocks to a Metro station before catching the train into Washington. By the time she reaches her office downtown, the commute has taken close to an hour.
Ahmad, 25, moved to the United States from Pakistan last year to work in policy research. She shares a three-bedroom apartment with two roommates, and her portion of the rent is about $1,100 a month.
“It’s manageable,” Ahmad said. “But when you start thinking about saving for the future — like actually buying a place someday — that’s when it starts to feel kind of far away.”
For generations, Americans considered homeownership one of the most recognizable markers of the American Dream. Purchasing a house long symbolized stability, upward mobility and middle-class security. But for many young people in the United States, navigating rising rents and home prices made that milestone harder to reach.
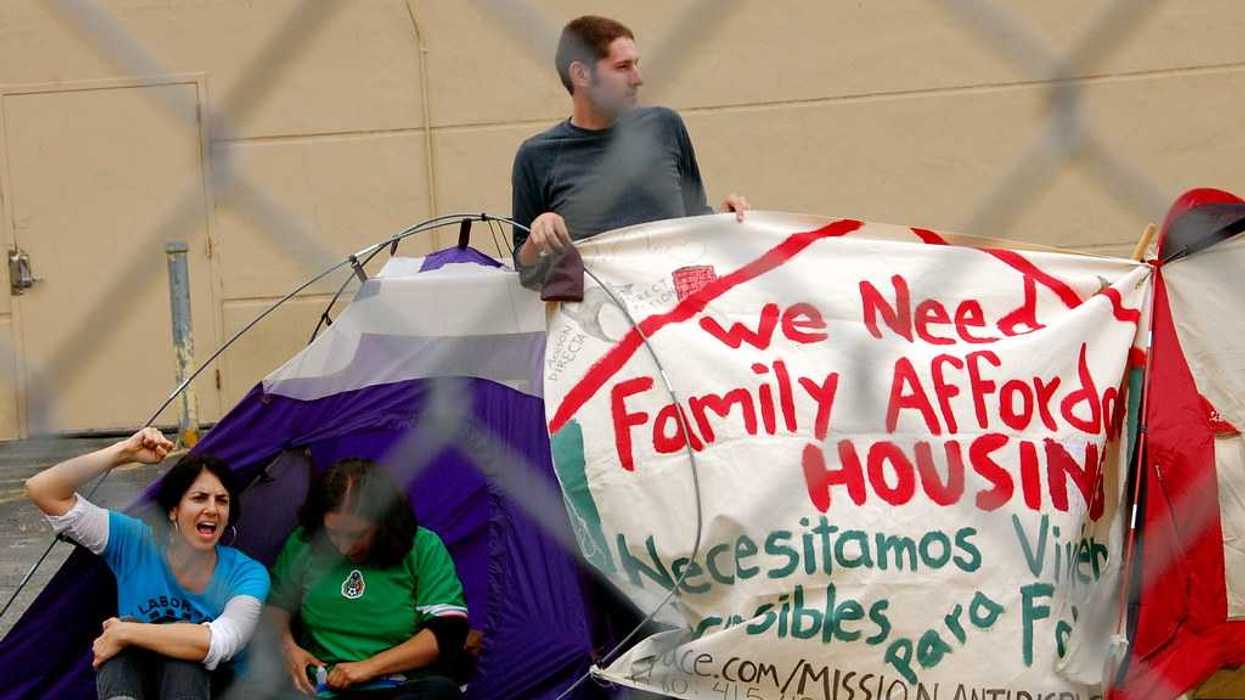
Housing affordability has moved to the center of economic anxiety and political debate in the United States.
The average first-time homebuyer in the United States rose to 40 years old, said Rep. Ann Wagner, R-Mo., during a congressional discussion about housing affordability. Wagner serves on the House Financial Services Committee, which has held several hearings on housing and urban development in recent months.
The statistic has circulated in policy debates and news coverage, reinforcing concerns that the traditional timeline for achieving financial stability, from starting a career to eventually buying a home, may be shifting further into adulthood.
Housing costs also shape how Americans define affordability, according to a New York Times/Siena poll from January. Many respondents expressed greater concern about what they consider major life milestones, including owning housing, having a family and retiring comfortably.
From the same poll, 77% of the respondents agreed that achieving a “middle-class lifestyle” became harder than it was a generation ago. In particular, several economic forces have converged to make buying a home more difficult.
According to data from real estate brokerage Redfin, a household would need to earn roughly $110,000 a year to afford a typical U.S. home. Meanwhile, the company estimated the median U.S. household income to be just over $86,000.
“The primary problem younger Americans face is that the cost of buying a new home has risen more quickly than incomes,” said Yonah Freemark, principal research associate at the Urban Institute.
Mortgage costs have compounded the pressure. At current interest rates, a typical buyer would spend about 38% of income on housing payments, compared with about 24% before the pandemic, according to an analysis from J.P. Morgan.
“High interest rates have made taking out mortgages prohibitively expensive,” Freemark said.
At the same time, home prices have continued to climb. The 2026 Housing Supply Gap Report from Realtor.com estimates the United States is short more than four million homes, a gap that has contributed to rising prices and limited inventory.
Freemark added that because home values have increased quickly, the amount of debt people must take on also rose quickly.
How cities grow and how quickly housing supply can respond to demand also shapes housing affordability, according to Wallace D. Lira, urban development researcher at MIT.
In many cities, residents increasingly seek housing close to jobs and transit.
“But construction and land-use decisions often take years to adjust to that demand,” Lira said. “When housing becomes scarce in economically dynamic cities, younger residents tend to absorb the shock first.”
Across the country, rising costs are making younger Americans reimagine their future.
Diego Ramirez, a 20-year-old business economics student at the University of California, Los Angeles, said housing costs in Southern California are something he and his friends talk about often.
Ramirez shares a two-bedroom apartment in Westwood, Calif., with three other students and pays about $1,000 a month each for a shared bedroom.
“I mean, everyone talks about owning a house someday,” Ramirez said. “But in L.A., it’s hard to picture how that actually happens.”
Ramirez said some of his classmates already expect they may have to move away from the region after graduating if they want to afford housing.
“A lot of people assume they’ll end up somewhere cheaper,” he said. “L.A. is great, but it’s expensive.”
Some economists have disputed the widely cited statistics about the rising age of first-time homebuyers.
Craig Richardson criticized the survey data from the National Association of Realtors 2025 Profile of Home Buyers and Sellers. Richardson said the data may not fully represent the broad population of buyers.
He cited Federal Reserve credit panel data that suggested the median age of first-time homebuyers is closer to 33 and had remained relatively stable since the early 2000s.
Still, economists broadly agree that housing affordability pressures have intensified.
During a hearing in the House Financial Services Committee, Stephen Moore, co-founder of Unleash Prosperity, said demand for housing surged after the pandemic while supply struggled to keep pace.
Moore cited a January poll from the National Association of Realtors and Hart Research showing 52% of Americans consider affordable housing a very important issue, while 85% consider homeownership essential to achieving the American Dream.
Young adults appear particularly pessimistic. Last year, 47% of young people in the U.S. who do not currently own a home said “they don’t foresee homeownership as an option for them ‘in the near future’,” said Moore.
Other economists emphasized deeper structural forces. Darrick Hamilton, chief economist at the AFL-CIO, said housing affordability challenges are tied to long-term economic trends that have made it harder for many households to accumulate and pass down wealth.
“[These conditions] are a result of policies that have concentrated capital and economic and political power,” Hamilton told the House Financial Services Committee. “Policies that prioritized speculation and profit over productive investment.”
As housing costs rise, the issue has also moved to the center of political debate in Washington.
During his Feb. 24 State of the Union address, President Donald Trump framed housing affordability as part of a broader challenge facing the country.
“Another pillar of the American Dream that has been under attack is homeownership,” Trump said.
He asked Congress to permanently prevent large investment firms from buying single-family homes.
“We want homes for people, not for corporations,” he said.
In Congress, lawmakers from both parties have debated a range of potential responses, including expanding housing construction, strengthening rental assistance programs and funding housing designed to remain permanently affordable.
Freemark said federal investment in housing could help stabilize the market.
“The federal government should be investing in housing that provides guaranteed affordability, such as through the construction of public and social housing,” he said.
For Ahmad, the debate often feels distant from the reality of her daily commute and monthly rent. She said she still hopes to buy a home someday, but the timeline feels uncertain.
“Back home, people talk about the American Dream like it’s something very clear,” Ahmad said. “Here it feels a little more complicated.”
For now, she said, the goal is simple. Keep saving and see what happens.
“But owning a home is always part of that picture,” she said.
André Hiroki is a journalism student at the Medill School of Journalism at Northwestern University, where he also studies economics. Originally from São Paulo, Brazil, he reports on business and public policy for Medill News Service’s “Medill on the Hill,” covering Congress and national issues.
The American Dream Now Comes with a Higher Price Tag was first published on California Latino News and was republished with permission. CALN is an affiliate of the Latino News Network.