
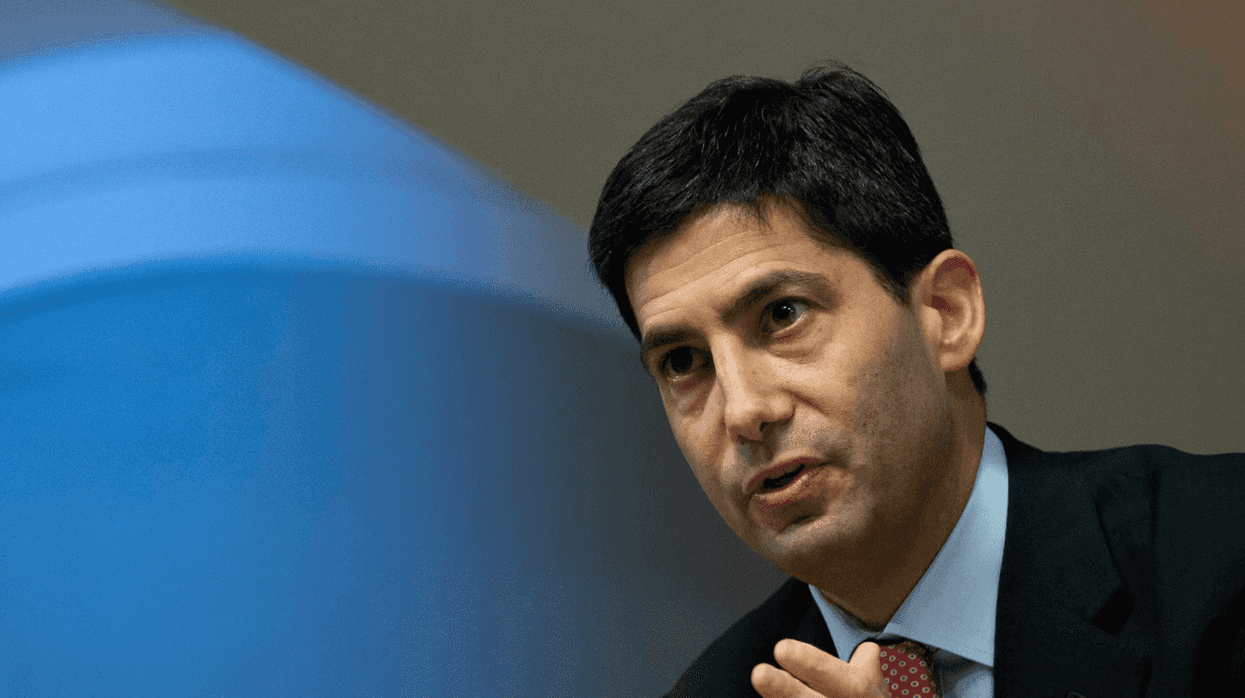
Since President Donald Trump named Kevin Warsh as his choice for Federal Reserve chair on Jan. 30, 2026, financial markets have focused on one question: Is he still the inflation hawk he once was, or is he now more comfortable with the lower interest rates that the president has long demanded?
We have a different take. Drawing on decades of research on central banking and an extended interview with Warsh conducted by one of us (Bowmaker) in 2023 for a forthcoming book on the Fed, we think the real change would be not in interest rates but in how the Fed communicates.
‘About right’
It’s no small matter. In modern central banking, policymakers’ pronouncements often shape the economy as much as their actual decisions.
The 2023 interview supports that view. Two themes ran through Warsh’s answers. The first was expected – a commitment to price stability. The second was more revealing: a desire to rethink how the Federal Reserve conducts its internal policy discussions and communicates them to the public.
In the interview, Warsh illustrated this with a story from 2006, when he was nominated to the Fed’s Board of Governors and sought advice from former chair Paul Volcker. Volcker told him the first task was to get interest rates “about right” – a phrase that, as Warsh noted, reflects the reality that policymakers never know the precise optimal level.
But Volcker added a second lesson he considered even more important: Make sure you look like you know what you are doing.
As Warsh interpreted it, modern central banking is not only about setting policy but also about presenting outcomes as the result of fulsome deliberation.
Warsh said he favors what he calls a “family fight” model of policymaking: open disagreement behind closed doors followed by unity in public. Recalling the 2007-09 financial crisis when the Fed was led by Ben Bernanke, he described arguments running their course in the chair’s office before members of the Fed’s rate-setting committee, known as the Federal Open Market Committee, reached their final decision and spoke collectively.
According to Warsh, large institutions – especially in times of crisis – need to project a single voice.
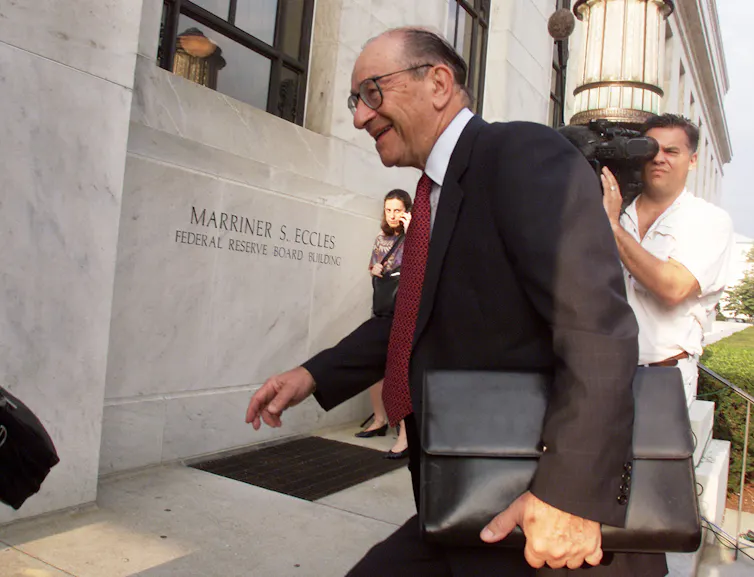 Although Alan Greenspan was the first chair to publicly announce the Fed’s decisions, the central bank remained inscrutable under his tenure, with analysts sizing up his briefcase to guess interest rate decisions. Mark Wilson/Newsmakers via Getty Images
Shifting toward openness
In a 2014 review for the Bank of England, Warsh recommended that their policy meetings begin with an unrecorded discussion – essentially the same “family fight.”
His concern was that transcripts, even when released years later, can shape how officials speak. If policymakers know their words will eventually be scrutinized, they tend to hedge and qualify their views rather than speaking plainly. In that sense, the effort to avoid appearing wrong can weaken decision-making.
That position puts him at odds with the Federal Reserve’s path over the past three decades – all in the name of reducing uncertainty, stabilizing expectations and improving policy effectiveness.
Beginning in 1994, under Alan Greenspan, the Fed started publicly announcing its interest rate decisions, a major break from earlier practice when markets had to infer policy changes.
Bernanke expanded that shift after the financial crisis, introducing quarterly press conferences and forward guidance on interest rates, as well as publishing FOMC participants’ projections – the so-called “dot plot.”
His successors, Janet Yellen and Jerome Powell, largely kept the framework in place, with current chair Powell holding a press conference after every meeting and trying to replace “Fed speak” with clearer language. The result is a central bank far more open than at any point in its history, explaining not only its decisions but also how it interprets the economy.
Fed credibility
Warsh is skeptical about this approach. He worries that publishing policymakers’ projections engenders “a troubling convergence of views,” as he said in the 2023 interview, stifling genuine disagreement inside the committee.
In his view, short-term forecasting offers limited benefit while subtly shaping how officials think about policy.
Warsh’s concern extends to communication more broadly. In his view, expansive messaging can make it harder to adjust policy as conditions change. As he said in the interview, extensive communication constrains a central banker’s “ability to change his mind,” yet “a central bank that can’t change its mind isn’t credible.”
For Warsh, credibility comes from adaptability rather than consistency – a stance that could call into question practices such as the dot plot.
Predictable vs flexible
Why does this all matter?
Modern financial markets respond as much to signals as they do to actions. Investors do not wait for interest rates to change; they adjust their behavior based on expectations of the central bank’s moves. Forward guidance and projections reduce uncertainty by helping markets anticipate policy.
A shift toward less explicit signaling would not necessarily make policy tighter or looser, but we believe it would make it less predictable – even though speaking with a single voice might partially offset this. Market reactions could become more sensitive to incoming data due to fewer clues about the Fed’s intentions.
The implications extend beyond Wall Street. Mortgage rates, business investment and hiring decisions all depend on expectations about future borrowing costs. Clear communication stabilizes those expectations, while greater discretion gives policymakers flexibility to respond to surprises.
Warsh’s approach, based on the 2023 interview, suggests he wants to trade some of that predictability for flexibility. In our assessment, the public may hear less about where policy is heading but see faster changes when economic conditions shift.
We cannot predict whether Warsh will push for lower interest rates or follow Volcker’s advice to get policy “about right.” But his own words suggest he will try to reshape how the Federal Reserve debates, signals and justifies its decisions – and in modern central banking, changing communication can change policy itself.
Trump Fed pick Kevin Warsh could shake up the central bank with his ‘family fight’ model was originally published by The Conversation and is republished with permission.
Simon Bowmaker is a distinguished Clinical Professor of Economics at New York University.
Paul Wachtel is an Emeritus Professor of Economics at New York University.



The President Invited Iran to Bomb My Home