The Trump administration frames the immigration debate around borders, crime, culture, and national identity. This conceals an uncomfortable reality for the administration: America’s retirement system increasingly depends on immigrant labor to survive.
That dependence is not ideological. It is demographic, rooted in the shrinking ratio between workers paying into the system and retirees drawing benefits from it.
The Demographic Squeeze
Social Security operates on a simple premise. Current workers fund current retirees through payroll taxes. When President Franklin D. Roosevelt signed the Social Security Act into law in 1935, as a cornerstone of his New Deal, the system rested on a young and rapidly expanding workforce. There were more than 40 workers supporting each retiree, life expectancy was significantly shorter, and the ratio between contributors and beneficiaries strongly favored the system’s long-term stability.
That arrangement worked remarkably well for decades. But the underlying demographics have changed dramatically. Americans are living longer, birth rates have declined, and the massive Baby Boom generation is now moving fully into retirement. Today, fewer than three workers support each Social Security beneficiary, and that ratio is expected to fall even further in the coming decades.
To be sure, worker productivity has risen enormously since the 1930s due to technological advances, automation, and economic growth. A modern worker produces far more economic output than previous generations could have imagined. But higher productivity alone cannot fully offset the fiscal pressures created by a shrinking ratio of workers to retirees. Social Security depends not simply on productivity, but on a sufficiently large labor force paying payroll taxes into the system.
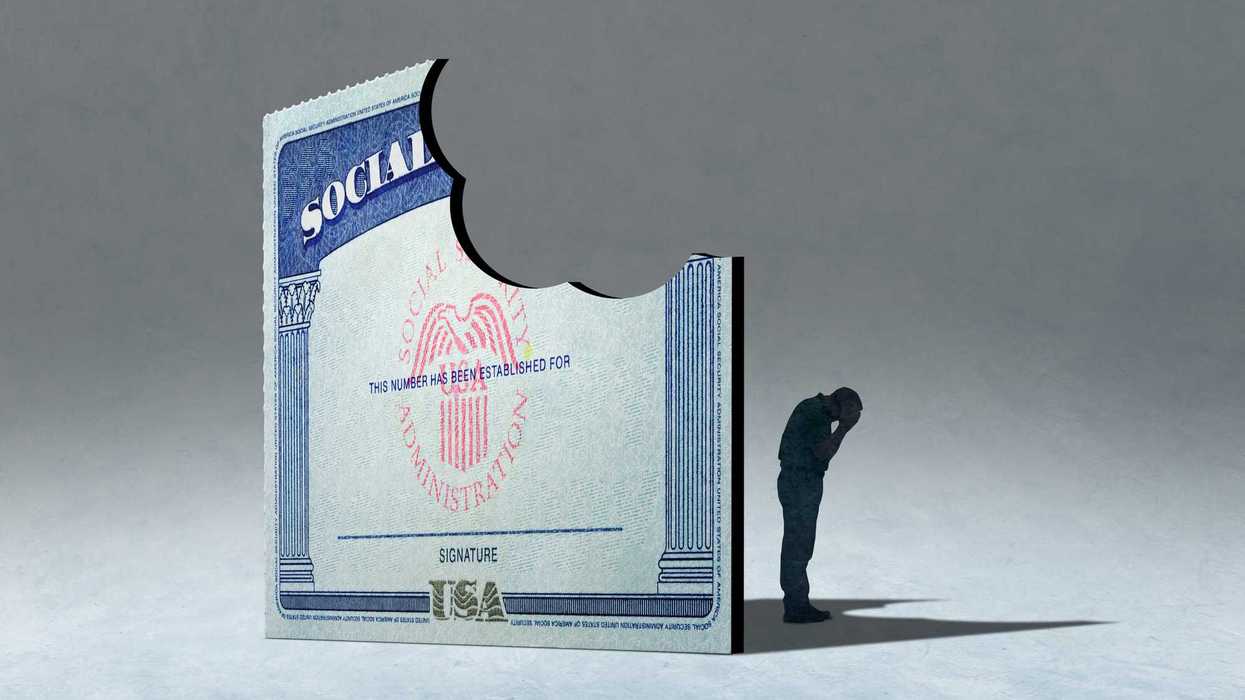
The system is already under strain. Social Security now pays out more in benefits than it collects in payroll taxes, forcing it to draw increasingly from its trust fund reserves. Those reserves are projected to be exhausted around 2033. Once depleted, the system would face automatic benefit reductions of roughly 23 percent unless Congress intervenes. At the same time, Medicare Part A, which funds hospital care for seniors, faces a similar timetable for insolvency, suggesting that the financial pressures created by an aging society extend well beyond Social Security alone.
Immigration and the Social Security Workforce
This is where immigration enters the picture in ways many Americans may not fully appreciate. Immigrants are disproportionately concentrated in working-age populations. They fill jobs, pay payroll taxes, consume goods and services, and help sustain the labor force supporting an aging society. Even undocumented immigrants contribute billions annually into Social Security through payroll deductions, often without ever qualifying to collect benefits themselves.
The Trump administration’s aggressive immigration crackdown, therefore, carries consequences that extend well beyond the border. Reducing the number of future workers entering the labor force also reduces the number of taxpayers supporting Social Security and Medicare. The politics of immigration restriction are colliding directly with the arithmetic of an aging nation.
The Politics of Contradiction
This creates a political contradiction that neither party has been particularly eager to confront honestly.
Politicians in both parties avoid discussing the problem because nearly every available solution carries political risk. Raising payroll taxes is unpopular. Cutting benefits is politically toxic. Increasing immigration remains deeply polarizing. Even relatively modest proposals, such as gradually raising the retirement age or reducing benefits for wealthier retirees, trigger fierce backlash.
Democrats have often treated Social Security reform as politically untouchable, wary of alienating older voters and organized labor. Republicans, meanwhile, have increasingly built their coalition around older Americans while embracing policies that weaken the long-term financing of the system. Trump has repeatedly promised not to cut Social Security benefits while also proposing to eliminate taxes on Social Security income and aggressively reduce immigration.
Individually, those promises may sound politically attractive. Together, they create a fiscal trap. Taxes on Social Security benefits help finance both Social Security and Medicare, while immigration helps sustain the labor force paying payroll taxes into those systems. Removing revenue while simultaneously shrinking the future workforce places greater pressure on programs already strained by demographic imbalance.
Yet arithmetic has a way of asserting itself eventually, regardless of ideology or campaign slogans.
The Illusion of Stability
For years, the Social Security trust fund has masked the severity of the problem by allowing the government to draw down accumulated reserves. That cushion created the appearance that the system’s finances remained fundamentally stable even as the worker-to-retiree ratio steadily deteriorated underneath.
The trust fund itself emerged from reforms enacted in the 1980s, when lawmakers recognized that the retirement of the Baby Boom generation would eventually place enormous pressure on the system. In a rare bipartisan effort led by President Ronald Reagan and Democratic House Speaker Tip O’Neill, Congress responded by gradually increasing payroll taxes and raising the retirement age, generating large surpluses that accumulated over several decades. Those reserves were intended to help cushion the financial shock once millions of Baby Boomers began retiring.
For a time, the strategy appeared successful. The growing trust fund helped reassure Americans that Social Security remained financially secure, even as demographic trends quietly moved in the opposite direction. Politically, the existence of the reserves also made it easier for elected officials to postpone more difficult structural reforms.
But trust funds are not magic. They help mask long-term imbalance, creating the illusion of stability even as the underlying demographic pressures continue to worsen. The reserves buy time, but they do not eliminate the underlying arithmetic. Once those reserves are exhausted, the choices become immediate and unavoidable.
When Retirement Stops Working
For millions of middle-class retirees, the consequences would be severe. Consider a retired couple living largely on Social Security, modest savings, and perhaps a small pension. A 23 percent reduction in benefits could mean the difference between stability and financial distress. Mortgage payments, prescription drug costs, utilities, property taxes, and grocery bills would not suddenly fall simply because Washington failed to act.
For wealthier retirees, such cuts would be painful but manageable. For many middle-class and lower-income seniors, however, Social Security is not supplemental income. It is the foundation holding together retirement itself.
According to the Social Security Administration, roughly 40 percent of older Americans rely on Social Security for at least half of their income, while about 12 percent depend on it for 90 percent or more. For millions of retirees, the monthly check is what keeps food on the table and prevents poverty.
Increasingly, retirement itself is becoming less permanent. A growing number of older Americans are being, in effect, “fired from retirement” as rising housing, healthcare, insurance, and food costs outpace their savings. Recent reporting in The New York Times highlighted retirees returning to the workforce not because they want to stay active, but because they can no longer afford not to work. Some have taken part-time retail jobs, others returned to consulting or gig work, and many quietly depleted retirement accounts faster than expected during the inflationary shocks of the past several years.
A major reduction in Social Security benefits would intensify those pressures dramatically. Americans who spent decades believing they had reached financial stability could suddenly find themselves re-entering the labor market in their seventies, competing for work at the very moment age and health often make employment more difficult.
Without reforms, millions of older Americans could find themselves forced to delay retirement, return to work, draw down already limited savings, or make difficult choices between healthcare, housing, and daily living expenses.
The Choices Washington Keeps Avoiding
If Social Security is to remain solvent over the long term, immigration reform cannot be separated from the conversation. The politics of the issue may focus on the border, but the economics point toward the workforce.
None of the available solutions are politically easy, which helps explain why both parties have delayed serious action for so long. One option would be to raise payroll taxes, either by increasing the overall tax rate or by lifting the cap on taxable income so that higher earners contribute more. Another would involve gradually increasing the retirement age to reflect longer life expectancy, though critics argue this unfairly burdens lower-income Americans working physically demanding jobs.
But demographics suggest that some form of meaningful immigration reform will almost certainly be necessary as well. A country with declining birth rates and a rapidly aging population needs workers to sustain both economic growth and the tax base supporting retirement programs. Immigration alone cannot solve Social Security’s long-term financing problems, but without a sufficiently large labor force, the system becomes far more difficult to sustain.
Lawmakers could also reduce benefits for wealthier retirees while protecting lower-income seniors who depend heavily on Social Security for survival. Some economists have proposed partial privatization or expanded private retirement accounts, though such proposals remain deeply controversial after decades of political backlash.
Each proposal carries trade-offs. Raising taxes risks political backlash from workers already struggling with stagnant wages and rising costs. Raising the retirement age may seem reasonable to professionals working desk jobs but it feels far less realistic to construction workers, nurses, warehouse employees, or others whose bodies wear down long before their seventies.
Immigration presents perhaps the clearest example of America’s political and economic tensions colliding head-on and may ultimately become the defining contradiction shaping the future of Social Security itself. Americans increasingly want both tighter immigration restrictions and fully protected retirement benefits, even as the demographic realities sustaining those programs make those goals progressively harder to reconcile. Many voters support tighter border enforcement and lower immigration levels while also demanding that Social Security and Medicare remain fully funded. Yet those goals increasingly work against one another. Restricting the future workforce while preserving existing benefit commitments places greater strain on programs already facing demographic pressure.
But refusing to choose is itself a choice. For years, Washington has relied on the assumption that the crisis remained distant enough to postpone difficult decisions. Politicians could promise seniors that benefits would remain untouched while simultaneously assuring taxpayers that taxes would not rise. The trust fund helped sustain this illusion by masking the widening gap between political rhetoric and demographic reality.
That gap is now narrowing rapidly. The longer policymakers wait, the more abrupt and painful the eventual adjustments are likely to become.
Robert Cropf is a Professor of Political Science at Saint Louis University.